November opens with two events guaranteed to get people arguing about the economy. Australia gets the RBA’s rate decision on 3 November. America gets the midterms, with results expected to start rolling in from Wednesday morning, 4 November, Australian time. Read our midterms preview for the potential market implications.
Investors could be forgiven for wanting a quieter start. October brought sharp swings across Australian shares, US tech and crypto, culminating in post-earnings sell-offs in Amazon [AMZN], Intel [INTC] and Alphabet [GOOG]. Earlier in the month, NEXTDC [NXT] had already rattled local investors after delayed electricity upgrades forced a guidance cut. The spending ambitions and merger talks surrounding SpaceX [SPCX] and Tesla [TSLA] gave investors even more to digest.
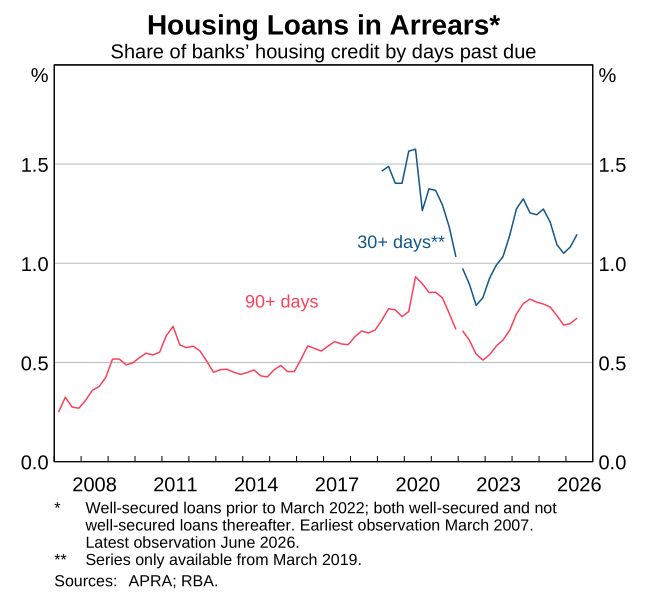
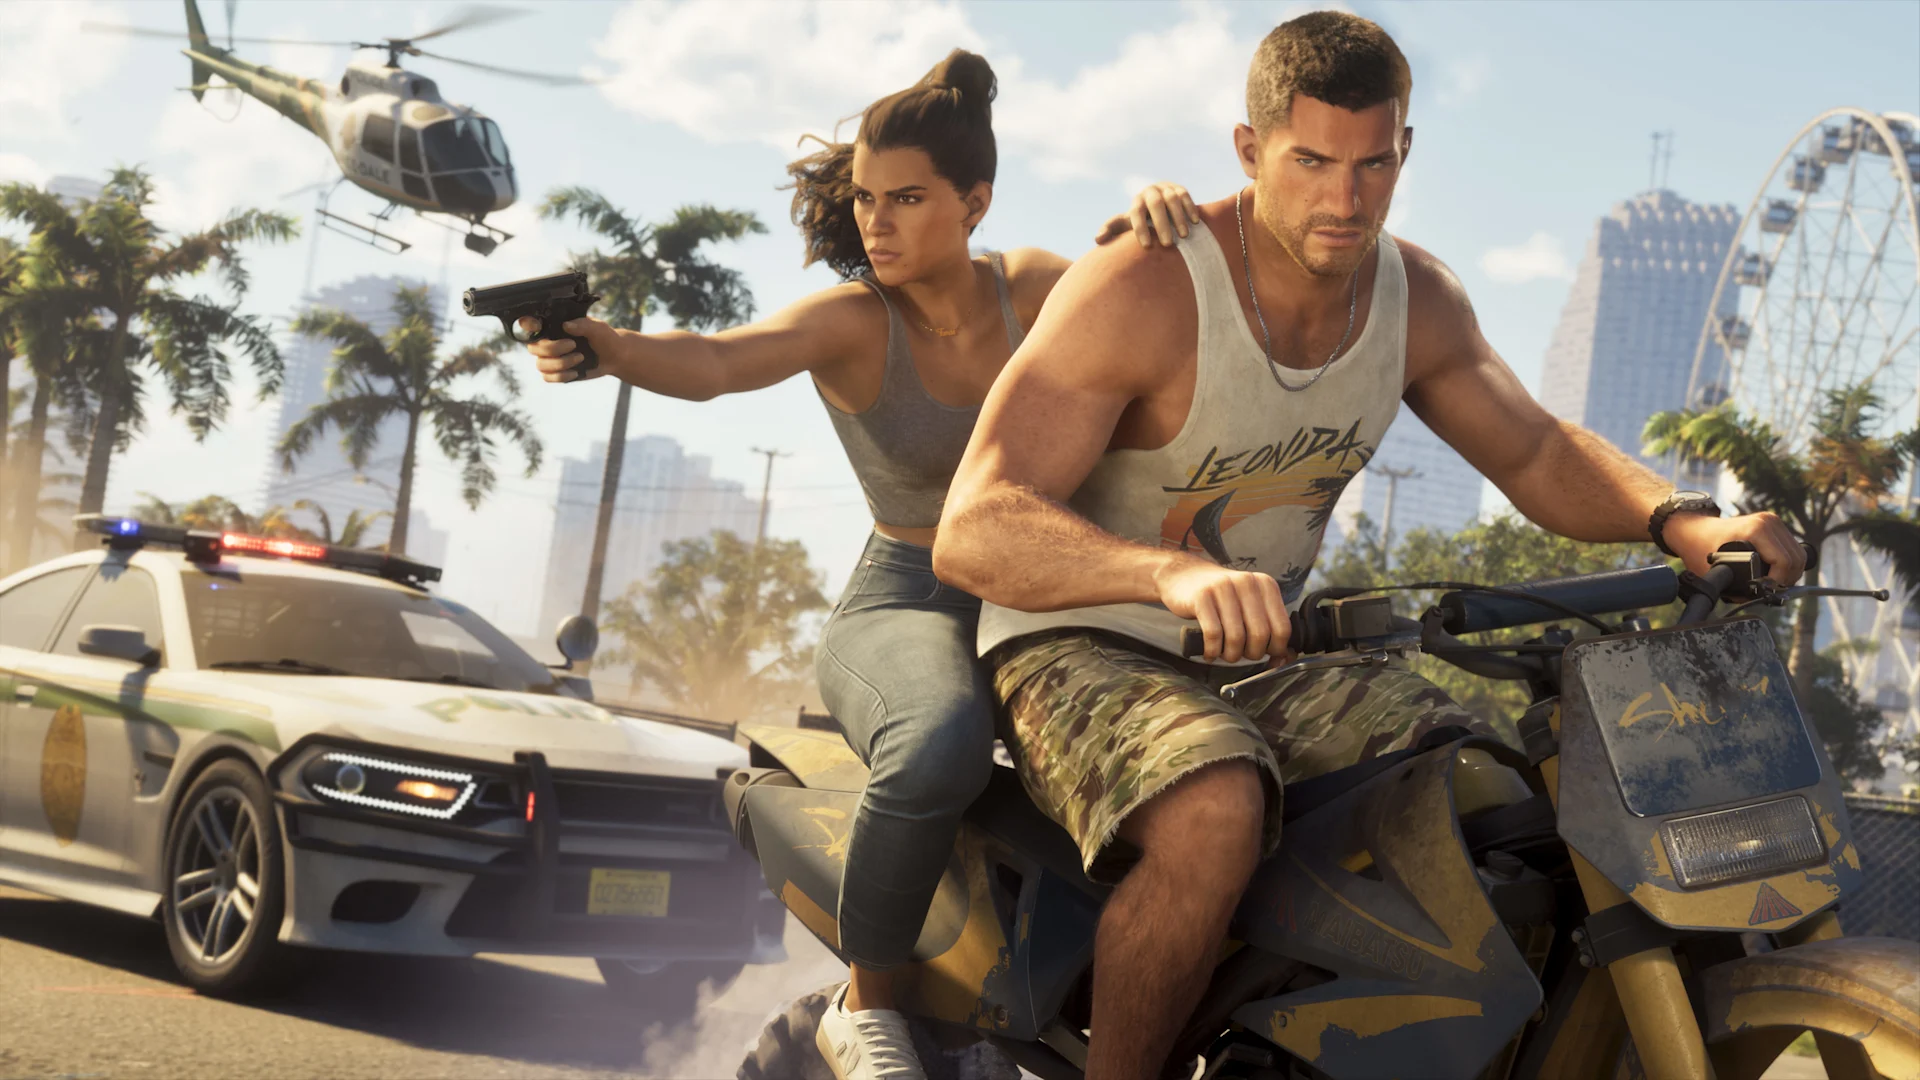
As November unfolds, Australian bank earnings will reveal whether pressure on household budgets is becoming pressure on profits. AI infrastructure updates will show how expansion plans are progressing, with clients still buying despite delivery delays and financing risks. Then comes Take-Two’s [TTWO] GTA VI launch, potentially one of the year’s biggest cultural events and likely to coincide with a rise in suspiciously timed sick days. Shareholders, though, need players to keep returning, and spending, long after everyone is well enough to work.