This week features two central-bank decisions: the Reserve Bank of Australia (RBA) on 3 November and the Bank of England (BoE) on 5 November. However, the BoE is expected to leave rates unchanged. The US midterm elections will take place on 3 November and could sway the balance of power in both houses of Congress. The week will also bring a slew of economic data, including the Institute for Supply Management (ISM) manufacturing and services reports and the US jobs report. Earnings season will remain busy, with Apple's report as the early-week headliner.
The Week Ahead: Apple earnings, US jobs report, ISM PMI data
CMC Markets
Table of contents
- 1.Apple Q4 earnings
- 2.ISM PMI reports
- 3.US jobs report
- 4.Economic & company events calendar
Apple Q4 earnings
Monday 2 November
Apple is expected to report fiscal fourth-quarter 2026 earnings growth of 7.4% year on year to $1.99 a share, with revenue forecast to rise 10.7% to $113.4bn. Gross profit margins are forecast at 47.5%, compared with 47.2% a year earlier. iPhone revenue is forecast to grow 15.3% to $56.5bn.
Investors will also keenly watch Apple's fiscal first-quarter outlook, with revenue expected to rise 6.1% to $152.6bn. iPhone revenue is forecast to rise by around 5% to $89.5bn, while gross profit margin is expected to decline sequentially to 46.3%.
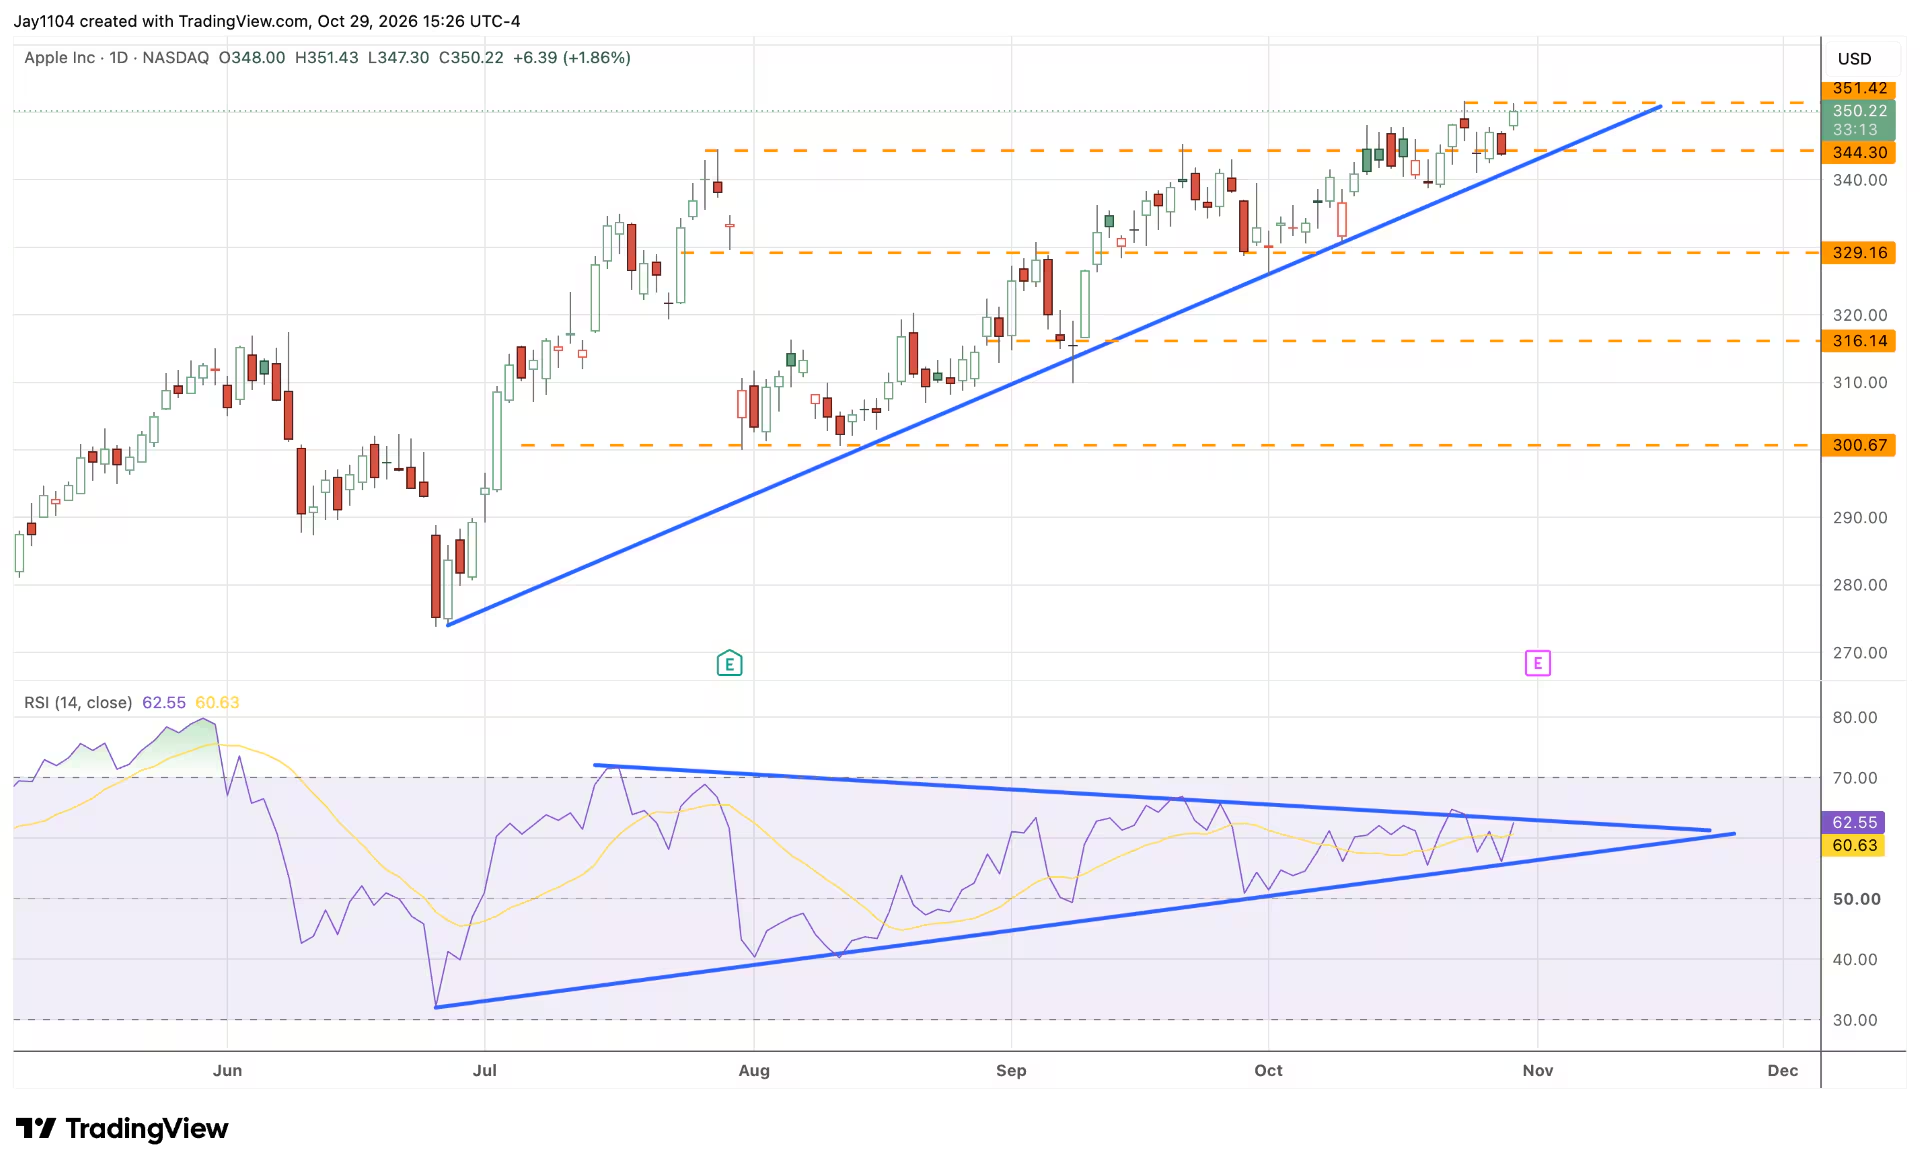
The stock is expected to move by about 4% after results. Call-option positioning suggests strong resistance at $350 and $355, while put options offer support around $310. However, overall options positioning is bullish. Once the company reports results and implied volatility falls, hedging flows could weigh on the stock and push it lower.
Meanwhile, the chart shows the stock has trended higher since early August. However, the RSI is starting to compress and move sideways. If the stock fails to break above $355, it could trade lower, potentially falling towards $330, a major support level last tested at the end of September.
Apple share price, June 2026 – present
Source: TradingView, Michael Kramer
ISM PMI reports
Monday 2 November
The ISM manufacturing purchasing managers' index (PMI) report will be released on the morning of 2 November, followed by the services report on 4 November. Both reports will matter, as they give markets a sense of overall US business activity. However, the figures that may stand out most are the ISM prices-paid indices in both reports. These are key indicators of inflationary pressures in the US, and both have been rising and are near recent highs, suggesting inflation remains elevated. The readings could also provide an early indication of what to expect from the October consumer price index report. Additionally, both ISM reports will include employment indices, which could offer valuable insight into labour-market health ahead of the US jobs report on 6 November.
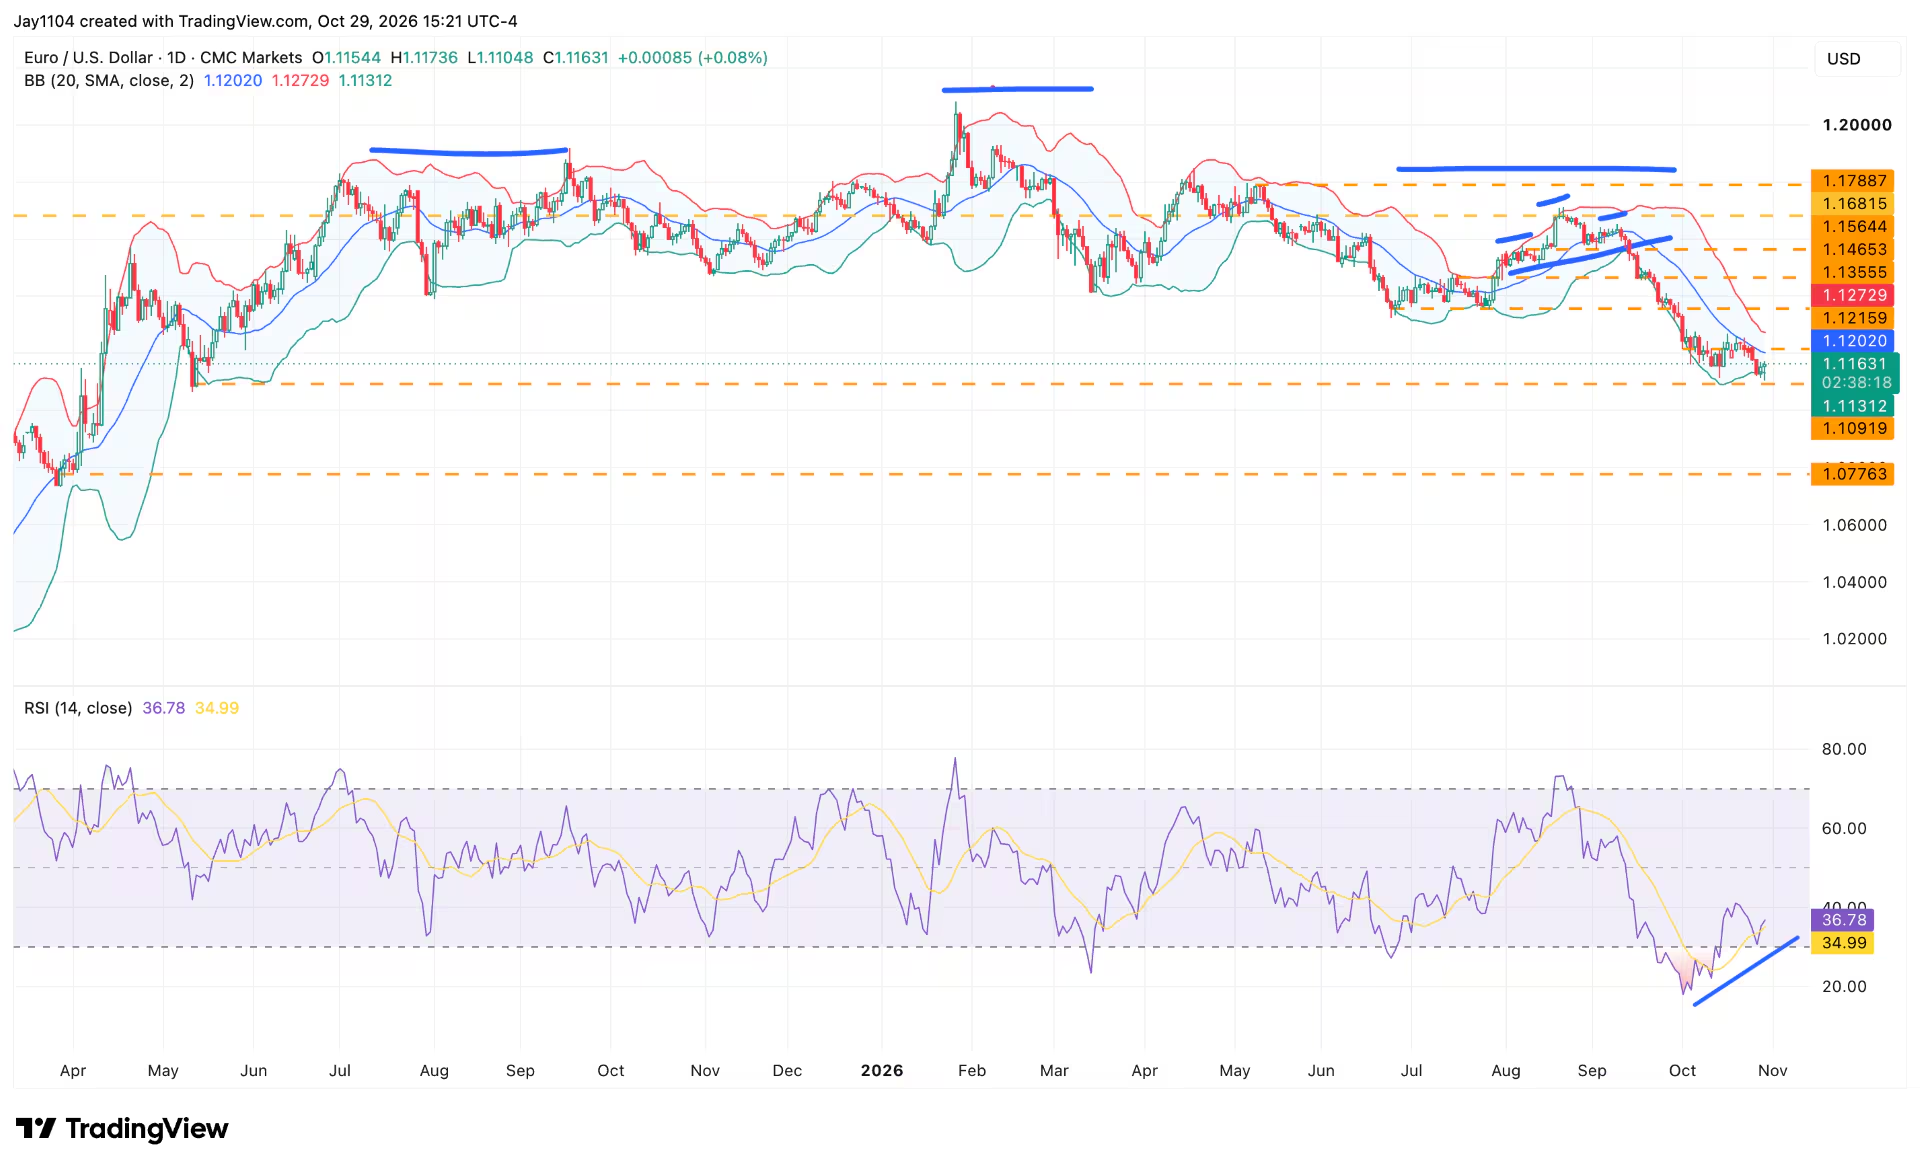
As a result, the ISM readings could play an important role in determining where EUR/USD ultimately heads. The currency pair has repeatedly tested support around $1.110 on 28 and 29 October but has so far failed to break below it. Additionally, early signs point to a potential bullish divergence, with the relative strength index (RSI) making a series of higher lows while EUR/USD continues to make lower lows. This could indicate that the euro may struggle to break below this key support level. If economic data comes in hotter than expected, the euro could finally break support and move towards the $1.07 region. However, until then, we need to remain open to a reversal, which could lead to a retest of $1.12.
EUR/USD, April 2025 – present
Source: TradingView, Michael Kramer
US jobs report
Friday 6 November
Job growth was weak in September. The October figure is expected to rebound, with around 60,000 jobs added and the unemployment rate remaining unchanged. The risk is that the figures come in higher than expected, which is possible given prior trends. Anything that points to higher interest rates and a stronger dollar could weigh on silver.
Silver has already broken below key support around $55 and continued lower, currently trading around $49. If the jobs report comes in stronger than expected, pushing interest rates higher and strengthening the dollar, silver could test the $47 area (or lower). A sustained break below $47 could open the way toward the next meaningful support levels further down. However, silver is deep in oversold territory, with its RSI having moved below the 30 threshold, while the price continues to track its lower Bollinger Band.
Silver, December 2025 – present
Source: TradingView
Economic & company events calendar
Major scheduled data releases, plus selected UK, US and other listed company results:
Monday 2 November
Australia: TD-MI inflation gauge (October), building permits (September)
Canada: S&P Global manufacturing purchasing managers' index (PMI) (October)
China: RatingDog manufacturing PMI (October)
Germany: Retail sales (September), HCOB manufacturing PMI (October)
New Zealand: Building permits (September)
Switzerland: Real retail sales (September)
US: Institute for Supply Management (ISM) manufacturing PMI (October), Federal Reserve Goolsbee speech, senior loan officer opinion survey (Q3)
Results: AdvancedAdvT (HY), Apple (Q4), Marriott (Q3), Palantir (Q3), Progressive (Q3), Vertex (Q3)
Tuesday 3 November
Australia: Reserve Bank of Australia (RBA) interest-rate decision, rate statement, monetary policy statement and press conference, AiG industry index (September), S&P Global composite and services PMIs (October)
New Zealand: Employment change, labour cost index, participation rate and unemployment rate (Q3)
Switzerland: Consumer price index (October)
US: Midterm elections, factory orders (September), JOLTS job openings (September)
Results: AMD (Q3), Amgen (Q3), Arista Networks (Q3), Associated British Foods (FY), dotdigital (FY), Focusrite (HY), Gattaca (FY), International Biotechnology Trust (FY), Marathon Petroleum (Q3), Pfizer (Q3)
Wednesday 4 November
China: RatingDog services PMI (October)
Eurozone: HCOB composite PMI (October), core and headline harmonised index of consumer prices (October, preliminary)
Germany: HCOB composite and services PMIs (October)
US: ADP employment change (October), S&P Global composite PMI (October), ISM services PMI (October)
Results: Braemar (HY), CVS Health (Q3), Lion Finance (Q3), Marks & Spencer (HY), McDonald's (Q3), McKesson (Q2), Qualcomm (Q4), Smiths News (FY), Trainline (HY), Uber (Q3)
Thursday 5 November
Australia: Trade balance (September)
Eurozone: Producer price index (PPI) (September)
Germany: Factory orders (September)
Japan: Bank of Japan monetary policy meeting minutes
UK: Bank of England interest-rate decision, minutes and monetary policy report, Governor Bailey speech
US: Challenger job cuts (October), initial jobless claims, non-farm productivity and unit labour costs (Q3), Fed Hammack speech
Results: Airbnb (Q3), Arm (Q2), Auto Trader (HY), BT (HY), ConocoPhillips (Q3), National Grid (HY), Parker-Hannifin (Q1), RS Group (HY), Southern (Q3), Tate & Lyle (HY)
Friday 6 November
Australia: Producer price index (PPI) (Q3)
Canada: Average hourly wages (year-on-year) and employment change (October), Ivey purchasing managers index (PMI) (October)
Eurozone: Retail sales (September)
Germany: Industrial production (September)
Japan: Labour cash earnings (September), BoJ Governor Ueda speech
US: Fed Williams speech, average hourly earnings, labour force participation, non-farm payrolls and unemployment rate (October), University of Michigan consumer expectations, consumer sentiment and inflation expectations (November)
Results: Charter Communications (Q3), Humana (Q3), IAG (Q3), Moderna (Q3), PPL (Q3), Record (HY), TBC Bank (Q3), Vistra (Q3)
Note: While we check all dates carefully to ensure that they are correct at the time of writing, the above announcements are subject to change.
Note: Announcements and dates are subject to change. Cross-check times in your timezone using the platform market calendar.
Disclaimer: This article provides general information only. It has been prepared without taking account of your objectives, financial situation or needs. It is not to be construed as a solicitation or an offer to buy or sell any financial instruments, or as a recommendation and/or investment advice. It does not intend to support an investment decision and it should not be relied upon by you in evaluating the merits of investing in any financial instruments. You should consider your objectives, financial situation and needs before acting on the information in this article. CMC Markets believes that the information in this article is correct, and any opinions and conclusions are reasonably held or made on information available at the time of its compilation, but no representation or warranty is made as to the accuracy, reliability or completeness of any statements made in this article. CMC Markets is under no obligation to, and does not, update or keep current the information contained in this article. Neither CMC Markets nor any of its affiliates or subsidiaries accepts liability for loss or damage arising out of the use of all or any part of this article. Any opinions or conclusions set forth in this article are subject to change without notice and may differ or be contrary to the opinions or conclusions expressed by any other members of CMC Markets.