The Week Ahead: US PCE, jobs report, Micron earnings

CMC Markets
6 minute read
|28 Sept 2026
Server racks with blinking lights in a modern data center room.
Table of contents
  • 1.
    US August PCE
  • 2.
    Micron Q4 earnings
  • 3.
    US jobs report
  • 4.
    Economic & company events calendar

The coming week will be important for markets, particularly in the US, with the latest personal consumption expenditures (PCE) price index and jobs report due. Given recent moves in US and global interest rates, markets will be watching both releases closely for signals about the Federal Reserve’s next potential move.

Other key data releases include US JOLTS job openings, ADP employment, ISM manufacturing, and final second-quarter GDP, all of which will inform broader market sentiment.

Micron Technology will also report results this week, as investors scrutinise its outlook and continue to assess the evolving landscape for AI-related investment themes.
US August PCE

Wednesday 30 September

Analysts forecast August’s headline PCE to rise by 0.4% month-on-month, up from 0.2% in July. On an annual basis, headline PCE is expected to remain unchanged at 3.7%. Core PCE is forecast to rise by 0.3% m/m, up from 0.2% in July, while the annual rate is expected to increase to 3.4% from 3.3%.

This is the Federal Reserve’s preferred inflation gauge. A hotter-than-expected print, especially in core, could reinforce a “higher for longer” Fed stance, push US yields higher, strengthen the USD, and prompt a risk-off move. That combination may weigh on the ASX 200 the following session, particularly given the index has already been trending lower this month. A softer outcome could do the opposite: lower yields, a weaker USD, improved global risk appetite, and a firmer open for Australian equities.

EUR/USD, April 2025 – present

Sources: TradingView

Micron Q4 earnings

Wednesday 30 September

Analysts are forecasting Micron’s fiscal fourth-quarter 2026 results to rise more than tenfold to $31.45 a share from $3.03 a year ago. Revenue for the Nasdaq-listed memory-chip company is expected to soar to $50.8bn, from $11.3bn a year earlier. Gross margins are also expected to improve significantly, rising to 85.9% from 45.7%.

Analysts and investors will also be assessing the company’s forward guidance. For Q1 of fiscal 2027, analysts anticipate earnings of $35.07 a share, revenue of $56.6bn and gross margin of 86%. The stock is expected to move around 9% after the earnings release.

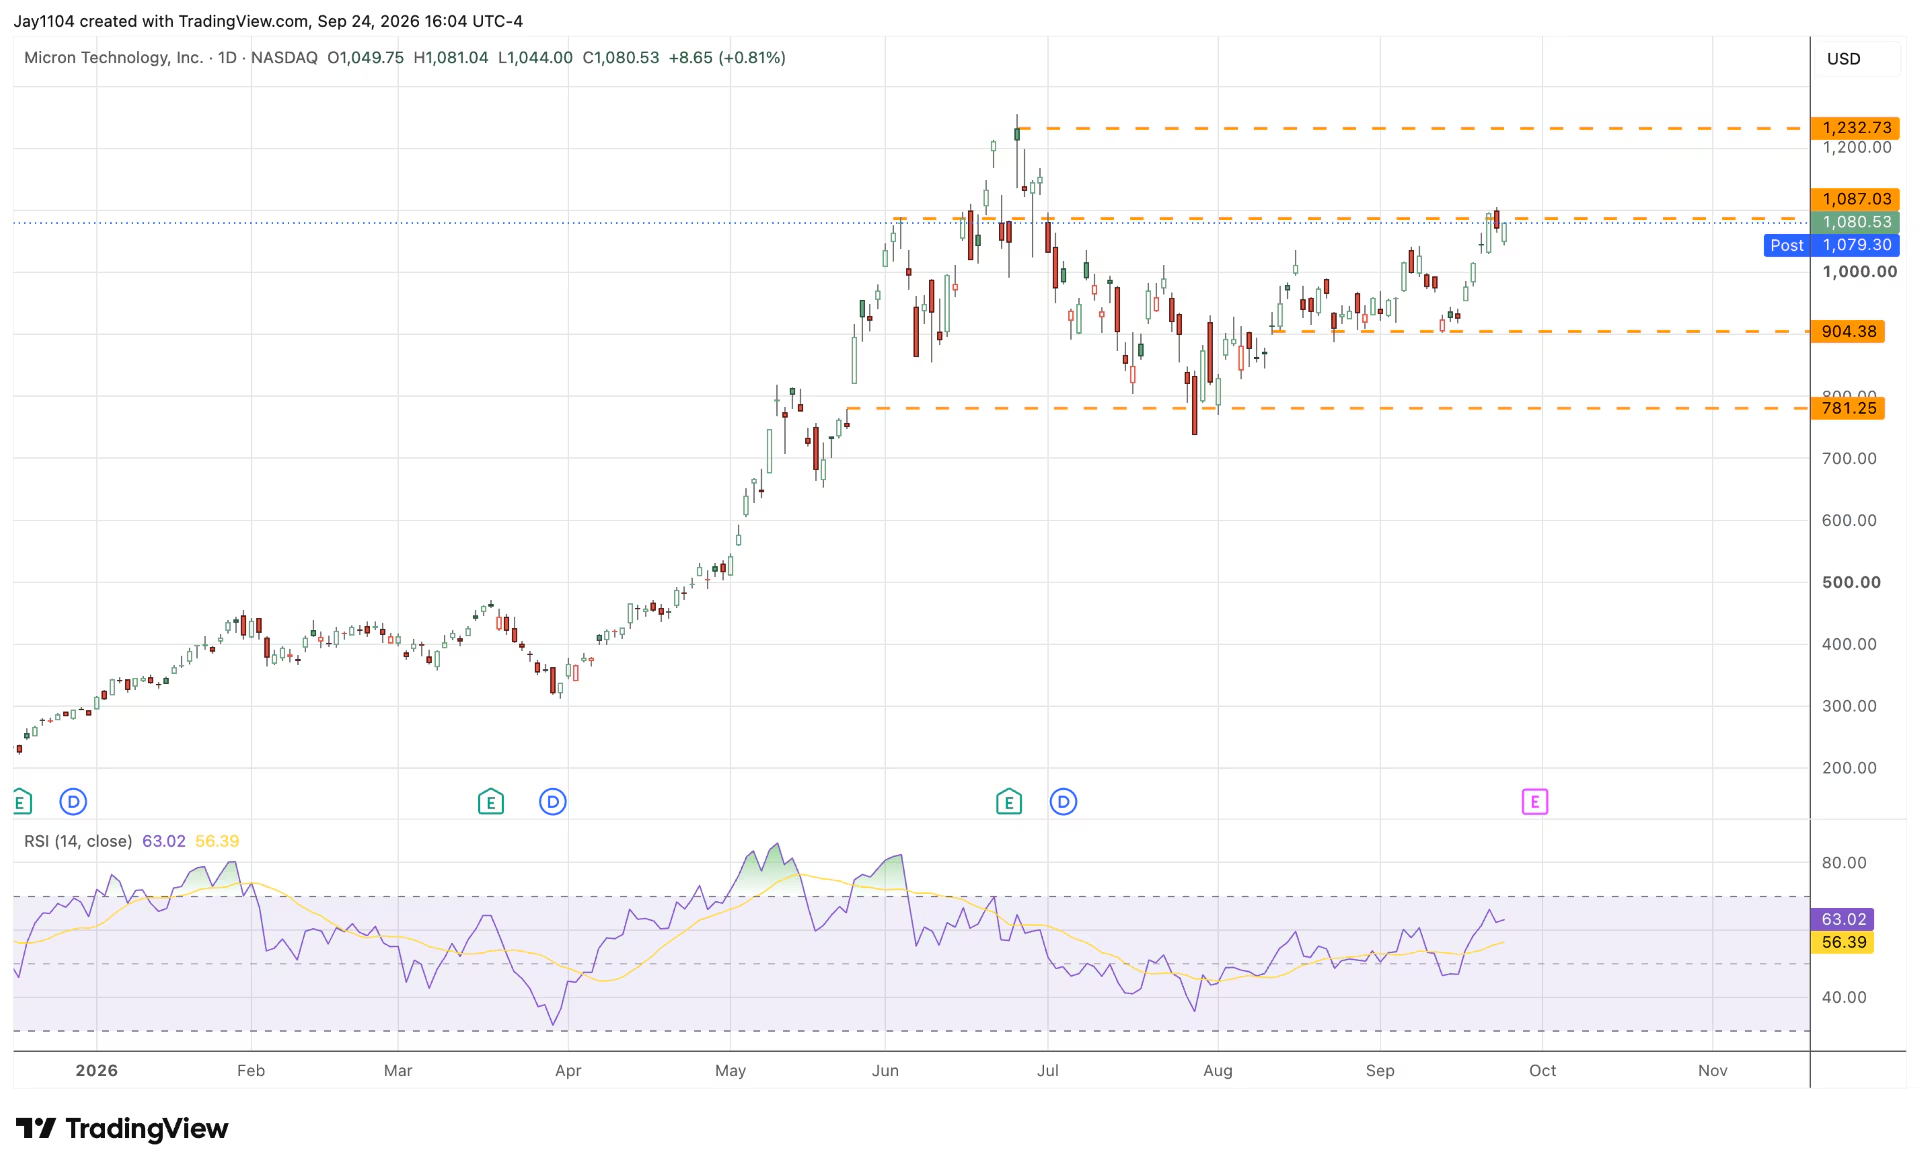
Options positioning in Micron ahead of its results is very bullish, suggesting that, once the company reports and implied volatility declines, hedging flows could weigh on the shares. Currently, ‘call gamma’ is heavily concentrated around $1,200, while ‘put gamma’ suggests support near $800.

Technically, the chart suggests the trading range may expand significantly. If the stock rises above $1,100, the shares could climb towards $1,235, the previous high last seen in June 2025. However, if the stock falls, support appears limited until around $900, where it formed a base from August through to mid-September. A break below $900 could see the shares fall back towards $780.

Micron earnings, January 2026 – present

Micron 28 September

Sources: TradingView, Michael Kramer

US jobs report

Friday 2 October

This will be the only labour-market report before the Fed’s next meeting at the end of October. Analysts expect non-farm payrolls to rise by 100,000 in September, down from 162,000 previously, while the unemployment rate is forecast to increase to 4.2% from 4.1%. Average hourly earnings are expected to rise by 0.3% m/m.

Investors will also be watching the August revisions closely, particularly as it was initially viewed as a strong month. Downward revisions could be seen as negative, while upward revisions would reinforce labour-market strength.

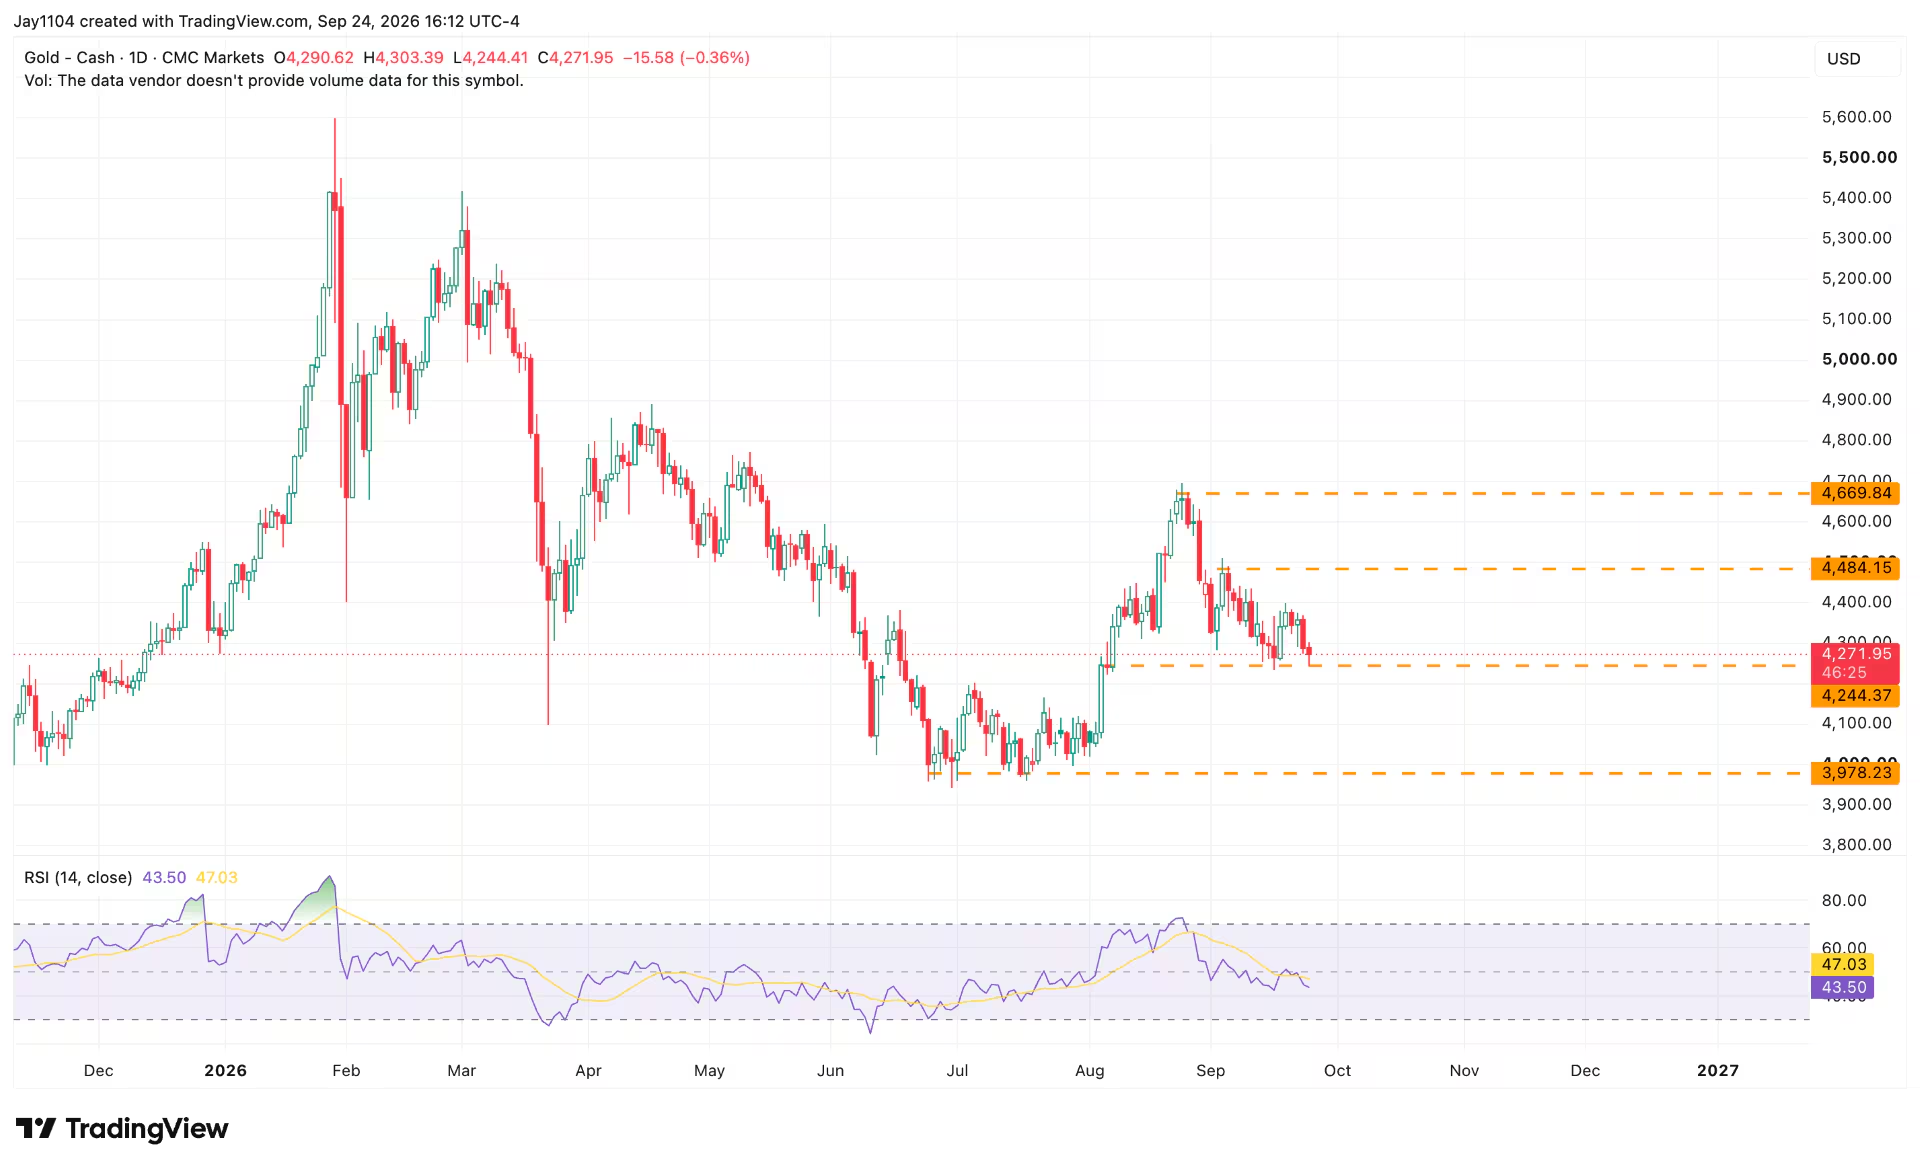
Given the relatively low expectations for September, a stronger-than-expected report is possible and could create a significant headwind for gold. The yellow metal is currently near major support around $4,250; a break below that level could open the way towards $4,000. Gold has recently traded inversely to interest rates and the US dollar, so a hot jobs report that pushes both higher – raising the perceived likelihood of a Fed rate hike – would probably weigh on the precious metal.

Conversely, a weaker report, accompanied by negative August revisions, could send gold sharply higher, potentially towards $4,500, or even $4,700, in the days that follow.

Gold, December 2025 – present

Gold 28 September

Sources: TradingView, Michael Kramer

Economic & company events calendar

Major scheduled data releases, plus selected UK, US and other listed company results:

Monday 28 September

  • Japan: Bank of Japan monetary policy meeting minutes

  • Results: Christie (HY), IDT (Q4), Jefferies (Q3), Kandi (HY), Likewise (HY), NetSol (Q4), Redcentric (FY), Tullow Oil (HY), US Solar (HY), Vail Resorts (Q4)

Tuesday 29 September

  • Australia: RBA interest rate decision, monetary policy statement and press conference

  • Eurozone: September business climate, September consumer confidence

  • UK: August consumer credit, August mortgage approvals

  • US: September consumer confidence, August JOLTS job openings

  • Results: AAR (Q1), AG Barr (HY), Card Factory (HY), CarMax (Q2), Carnival (Q3), Close Brothers (FY), Concentrix (Q3), S&U (HY), Uranium Energy (Q4), Wilmington (FY)

Wednesday 30 September

  • Australia: August consumer price index (CPI)

  • China: September manufacturing, non-manufacturing purchasing managers’ index (PMI)

  • Germany: September flash CPI, August unemployment rate

  • Japan: August industrial production, retail trade

  • UK: Q2 GDP, September BRC shop price index

  • US: September ADP employment change, August core personal consumption expenditures (PCE) price index, Q2 GDP, September Chicago PMI

  • Results: Avingtrans (FY), Cal-Maine Foods (Q1), Conagra Brands (Q1), FactSet (Q4), Jabil (Q4), Lords (HY), Micron Technology (Q4), NAHL (HY), Pinewood Technologies (HY), Saga (HY)

Thursday 1 October

  • Australia: September S&P global manufacturing PMI, August trade balance

  • Japan: Q3 Tankan large manufacturing index

  • UK: September S&P global manufacturing PMI

  • US: September Challenger job cuts, September S&P global manufacturing PMI, September ISM manufacturing PMI

  • Results: Acuity (Q4), James Halstead (FY), McCormick (Q3), Nike (Q1), Stolt-Nielsen (Q3)

Friday 2 October

  • Eurozone: September flash CPI, August unemployment rate

  • Japan: September Tokyo CPI, August unemployment rate

  • US: September average hourly earnings, non-farm payrolls, and unemployment rate, August factory orders

  • Results: J D Wetherspoon (FY)

Note: Announcements and dates are subject to change. Cross-check times in your timezone using the platform market calendar.

Disclaimer: This article provides general information only. It has been prepared without taking account of your objectives, financial situation or needs. It is not to be construed as a solicitation or an offer to buy or sell any financial instruments, or as a recommendation and/or investment advice. It does not intend to support an investment decision and it should not be relied upon by you in evaluating the merits of investing in any financial instruments. You should consider your objectives, financial situation and needs before acting on the information in this article. CMC Markets believes that the information in this article is correct, and any opinions and conclusions are reasonably held or made on information available at the time of its compilation, but no representation or warranty is made as to the accuracy, reliability or completeness of any statements made in this article. CMC Markets is under no obligation to, and does not, update or keep current the information contained in this article. Neither CMC Markets nor any of its affiliates or subsidiaries accepts liability for loss or damage arising out of the use of all or any part of this article. Any opinions or conclusions set forth in this article are subject to change without notice and may differ or be contrary to the opinions or conclusions expressed by any other members of CMC Markets.