Loading...
Loading...
The DAX is expected to consolidate near 25,000 as stronger Asian markets, China PMIs and quarter-end positioning support sentiment.
Chief Market Analyst
Wall Street's strong start to the week laid the foundation for a positive trading session across Asian markets. Investor sentiment was further supported by stronger-than-expected purchasing managers' indices from China, raising hopes that the world's second-largest economy may be moving towards a gradual recovery.
Both the manufacturing and services purchasing managers' indices came in slightly above the 50-point expansion threshold, indicating modest economic growth. Exports continue to provide the backbone of China's economy. Meanwhile, investors in Japan and South Korea continued to favour semiconductor and artificial intelligence stocks, extending the rally across regional technology sectors.
The final trading day of the second quarter was particularly significant, as it also provided an indication of investors' positioning ahead of portfolio rebalancing at the start of the new quarter. Technology stocks remain firmly in demand, suggesting that market momentum is still intact.
A similar pattern is emerging in Germany, where yesterday's winners remain today's favourites. Ahead of the opening bell, Siemens Energy and Infineon are once again among the strongest performers.
Later today, investors will focus on eurozone inflation data, US consumer confidence figures and the Job Openings and Labor Turnover Survey report. Against the backdrop of typically lighter summer trading volumes, the DAX is expected to continue consolidating around the 25,000-point level.
The DAX is struggling for direction as investors split between Wall Street optimism and a more defensive summer stance. Infineon is still benefiting from the AI and semiconductor trade, while SAP and Bayer remain under pressure amid profit-taking and legal uncertainty.
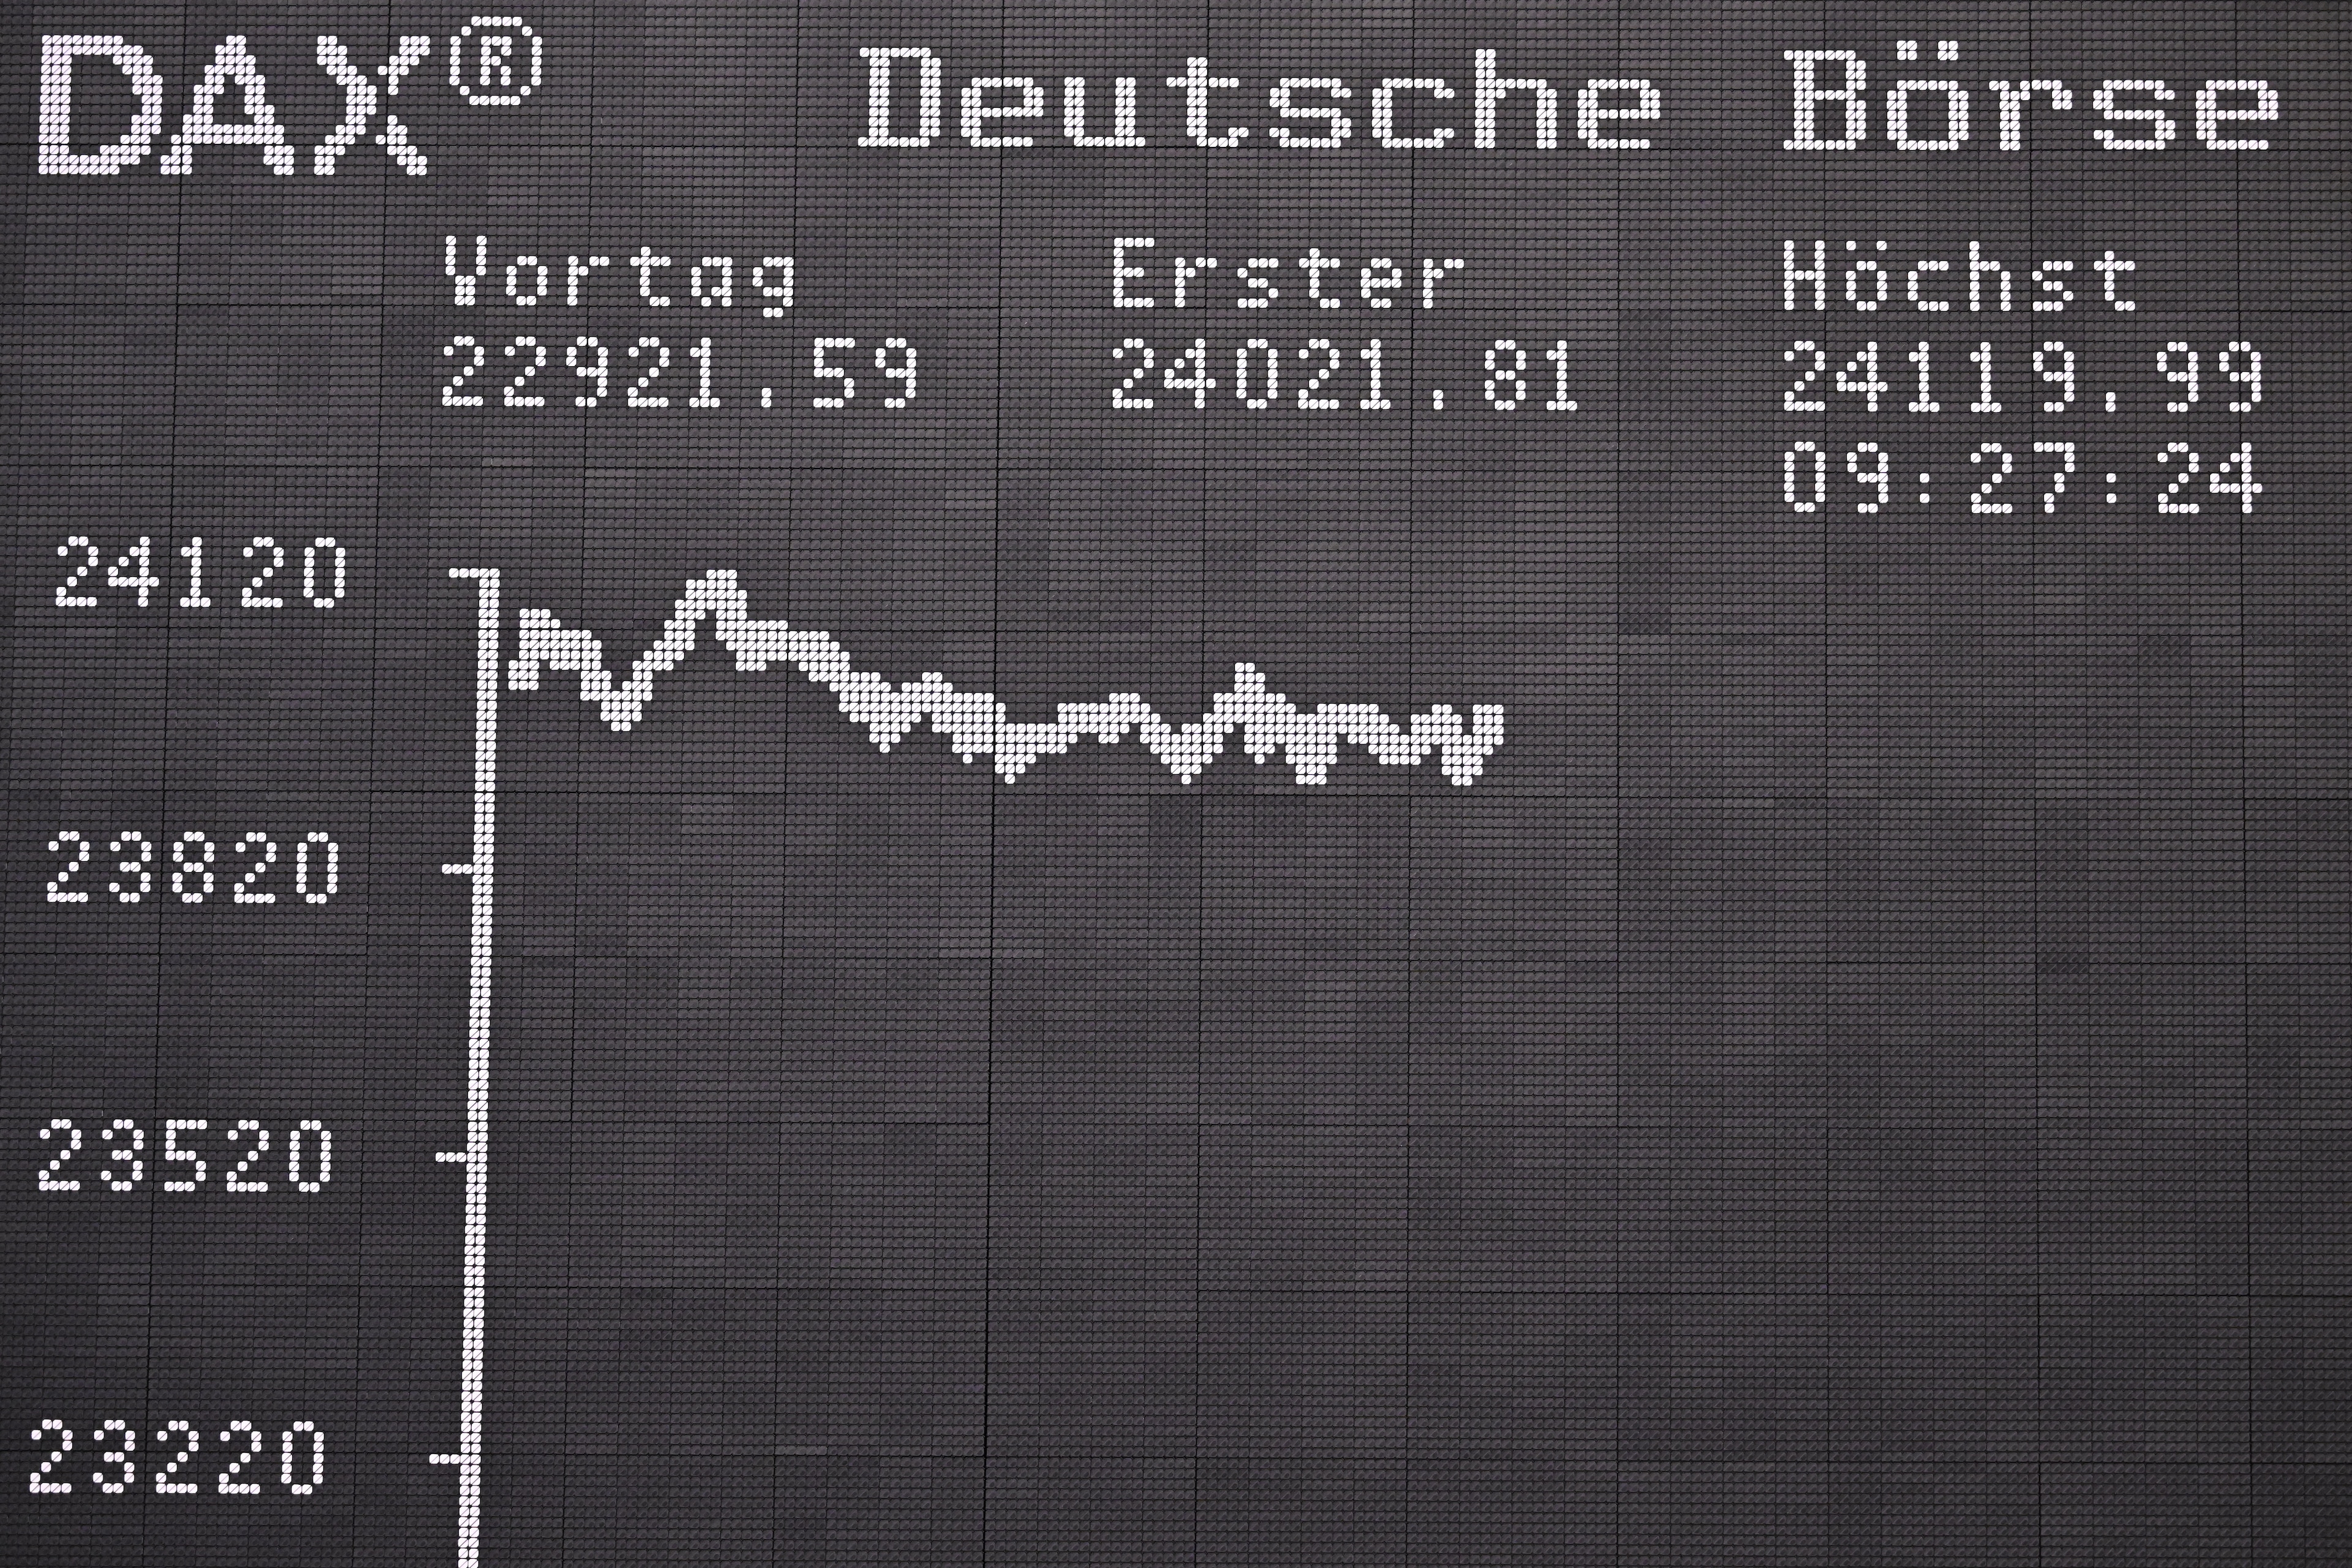
The DAX is still hovering around the 25,000-point area after Thursday's close above that level, but investors are treating the US-Iran agreement as fragile rather than resolved. Oil is off its recent highs but has edged around the $80 area again, while Friday's European derivatives expiry could keep Frankfurt trading choppy despite the US Juneteenth holiday.
The DAX is set for a steadier open near 24,300 after yesterday's rebound, but the tone remains fragile as investors keep trimming technology and AI names. With Middle East headlines still shaping sentiment and defensive sectors holding up better, the index may stay trapped in a relatively tight range.