Published: Friday, 25 September 2026 at 12.30pm (UK)
The coming week will be important for markets, particularly in the US, with the latest personal consumption expenditures (PCE) price index and jobs report due. Given recent moves in US and global interest rates, markets will be watching both releases closely for signals about the Federal Reserve’s next potential move.
Other key data releases include US JOLTS job openings, ADP employment, ISM manufacturing, and final second-quarter GDP, all of which will inform broader market sentiment.
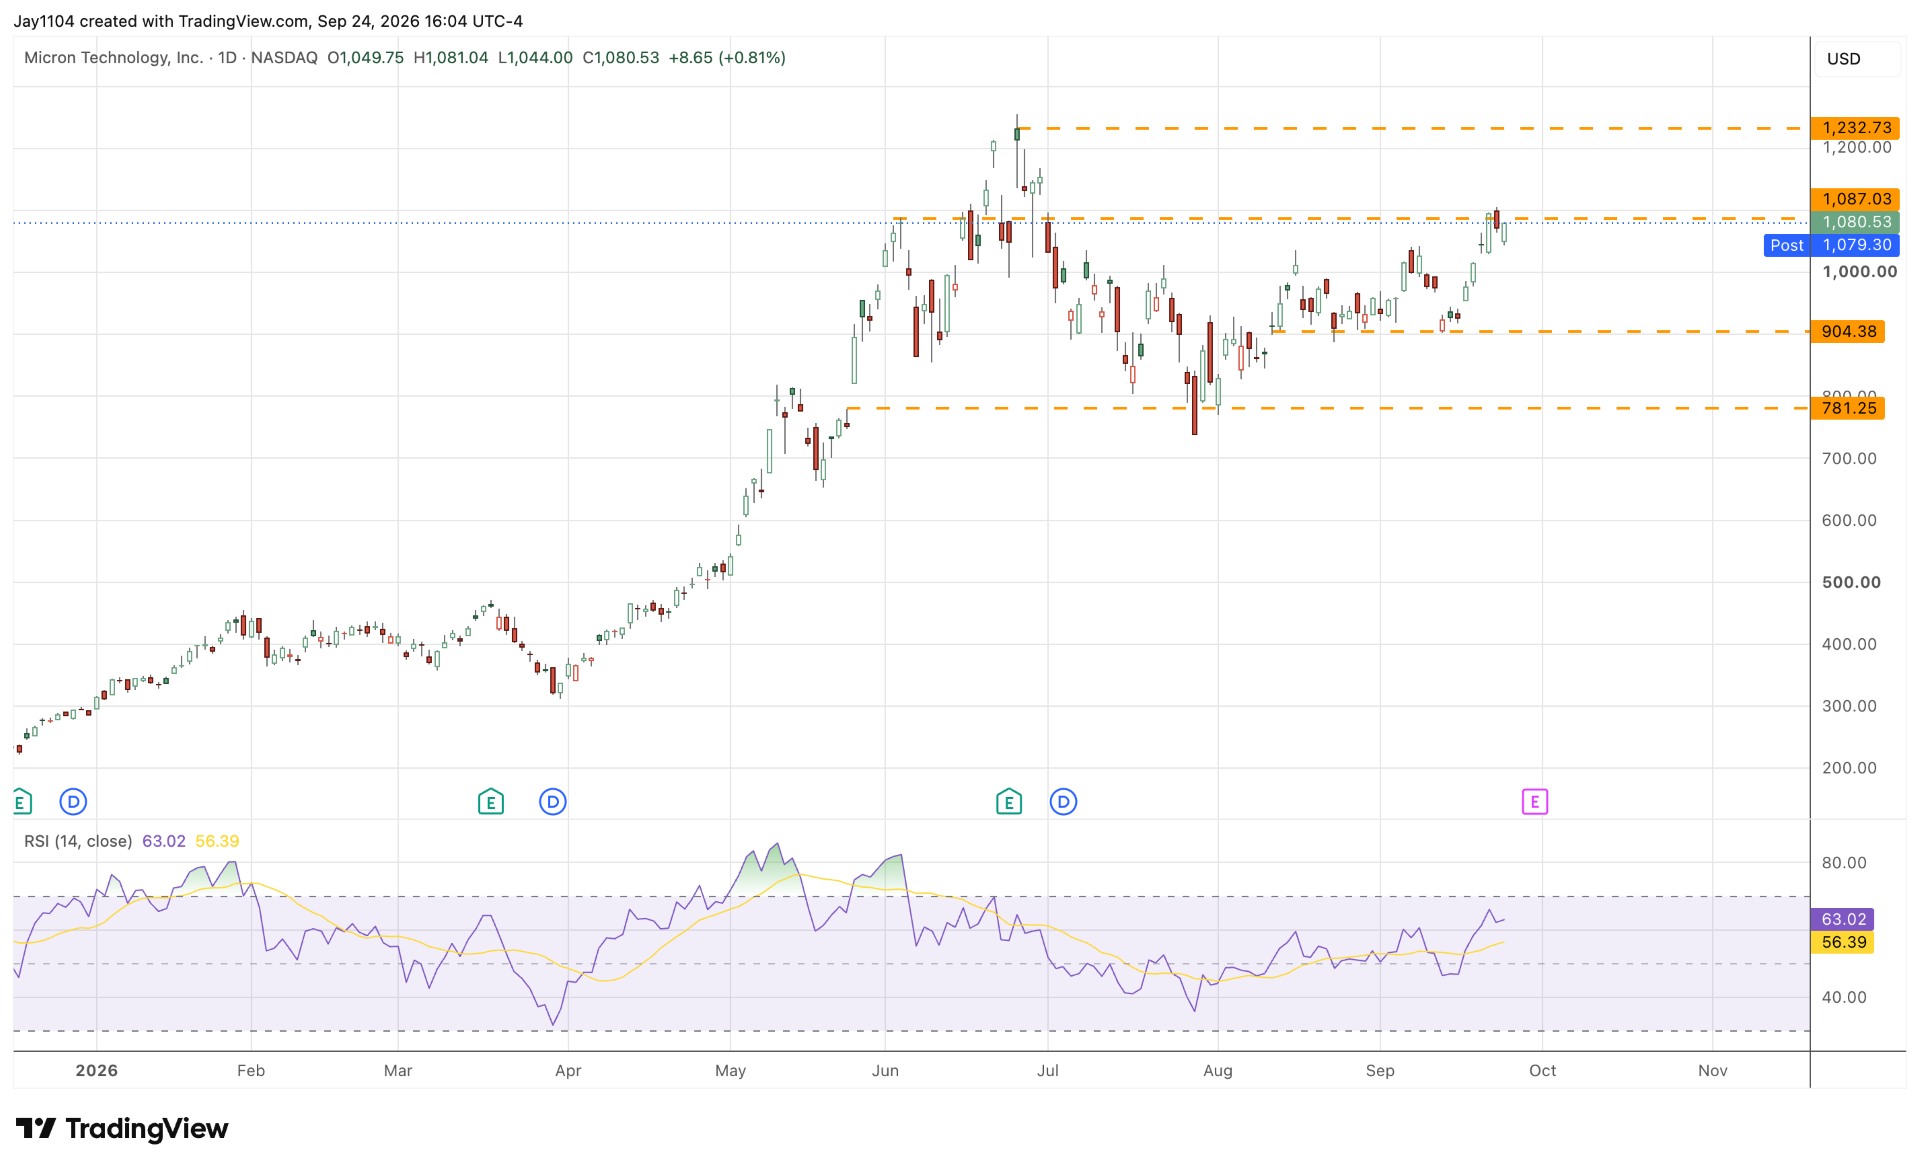
Micron Technology will also report results this week, as investors scrutinise its outlook and continue to assess the evolving landscape for AI-related investment themes.
US August PCE
Wednesday 30 September
Analysts forecast August’s headline PCE to rise by 0.4% month-on-month, up from 0.2% in July. On an annual basis, headline PCE is expected to remain unchanged at 3.7%. Core PCE is forecast to rise by 0.3% m/m, up from 0.2% in July, while the annual rate is expected to increase to 3.4% from 3.3%.
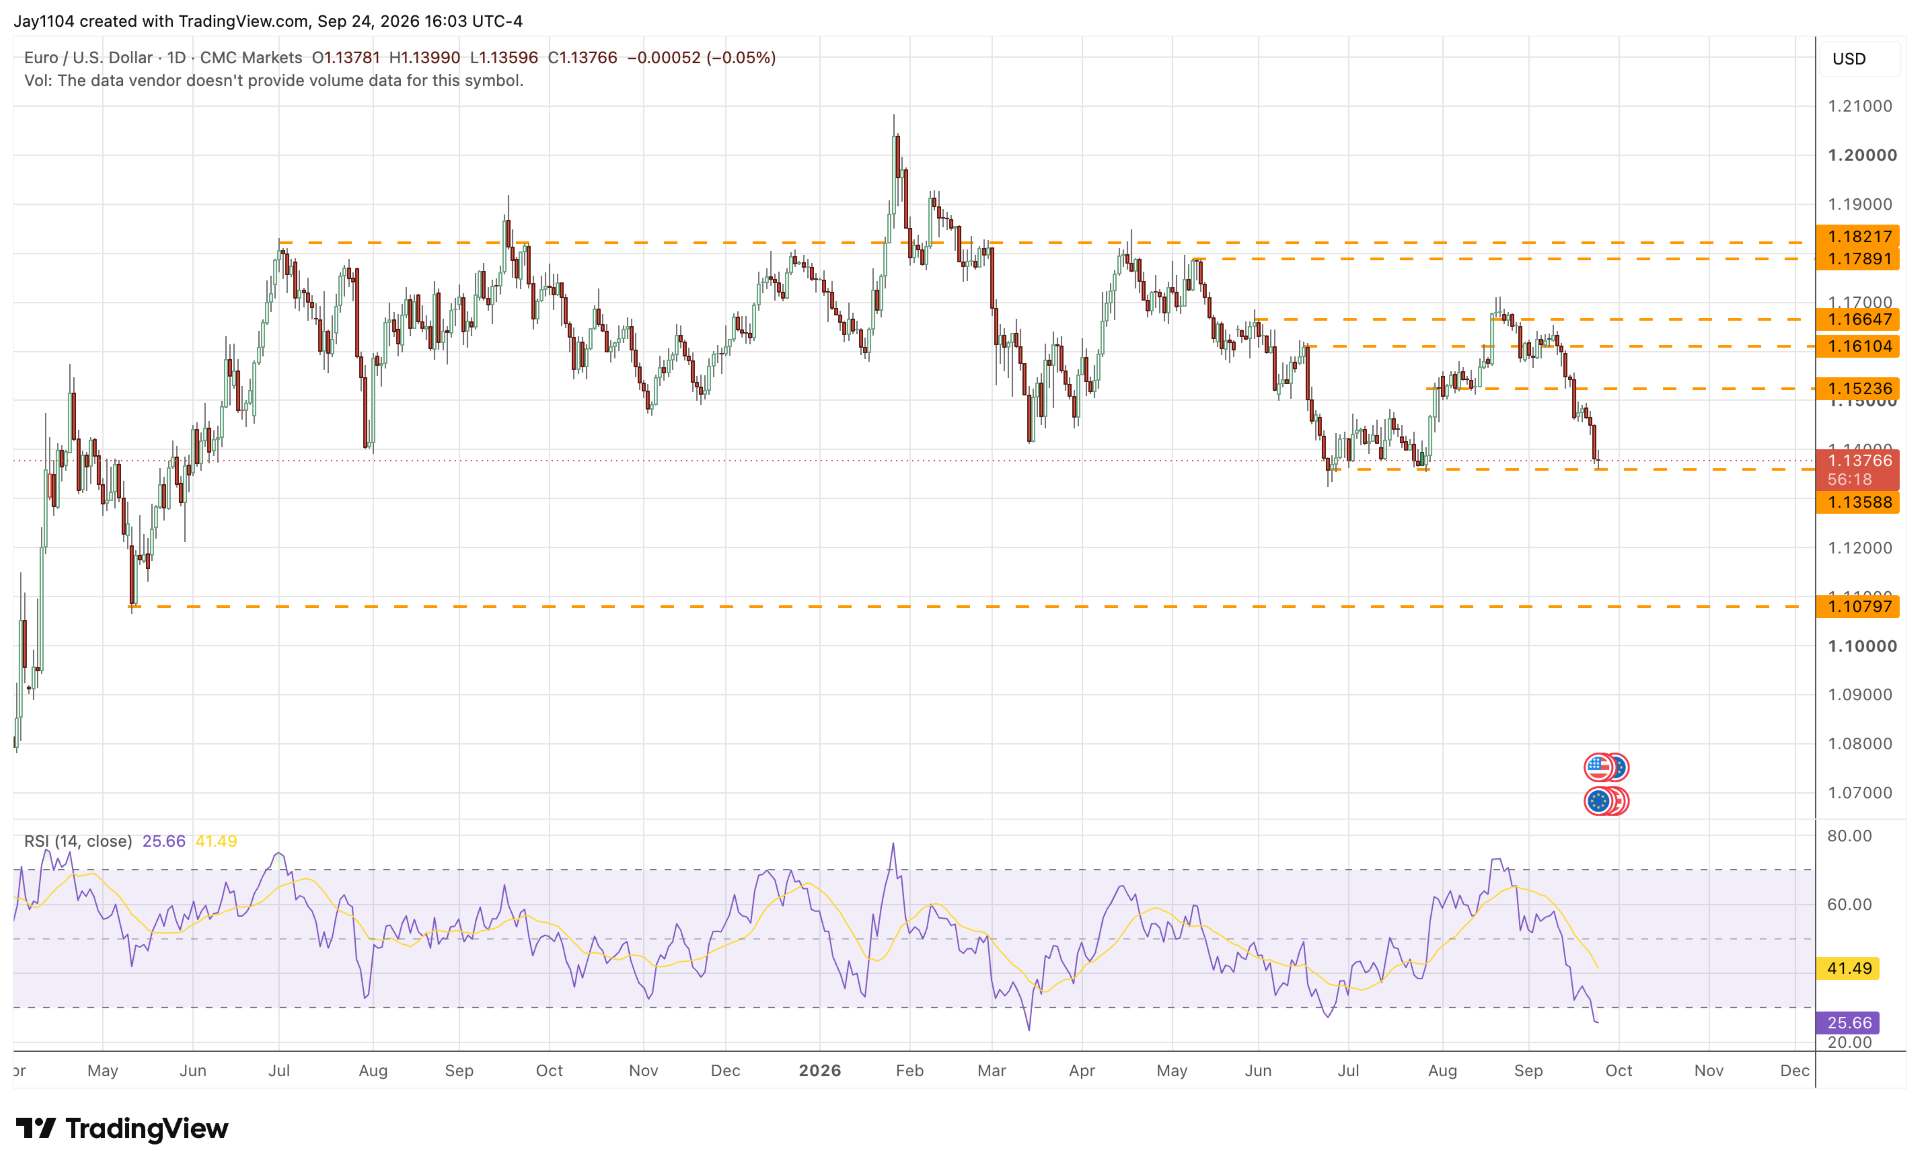
EUR/USD may be in a precarious position ahead of these reports. A second consecutive strong jobs report, combined with a hot PCE reading, particularly in the core measures, could weigh significantly on the pair. EUR/USD is currently near support at $1.1379. A break below this level could open the way to the next support area around $1.1080.