It looks set to be a busy week ahead, given the sudden departure of former Nvidia CEO Jensen Huang, ahead of the company's third-quarter results. Additionally, after a hotter-than-expected US consumer price index (CPI) report, the US Federal Reserve will release its October meeting minutes, while the UK and Japan unveil October inflation reports.
Nvidia Q3 earnings
Tuesday 17 November
The Nasdaq-listed AI infrastructure company is expected to report fiscal third-quarter 2027 revenue growth of 91.3% to $109bn, with earnings increasing by 90.3% to $2.47 a share. Gross margins are expected to come in at 74.1%, down from 75% in the fiscal second quarter. The company is expected to post fiscal Q4 2027 guidance that shows earnings growth of 69.5% to $2.75 a share, with revenue up 84.4% to $125bn, while margins contract to 71.7% sequentially. Nvidia shares are expected to move about 8% to 9% after earnings.
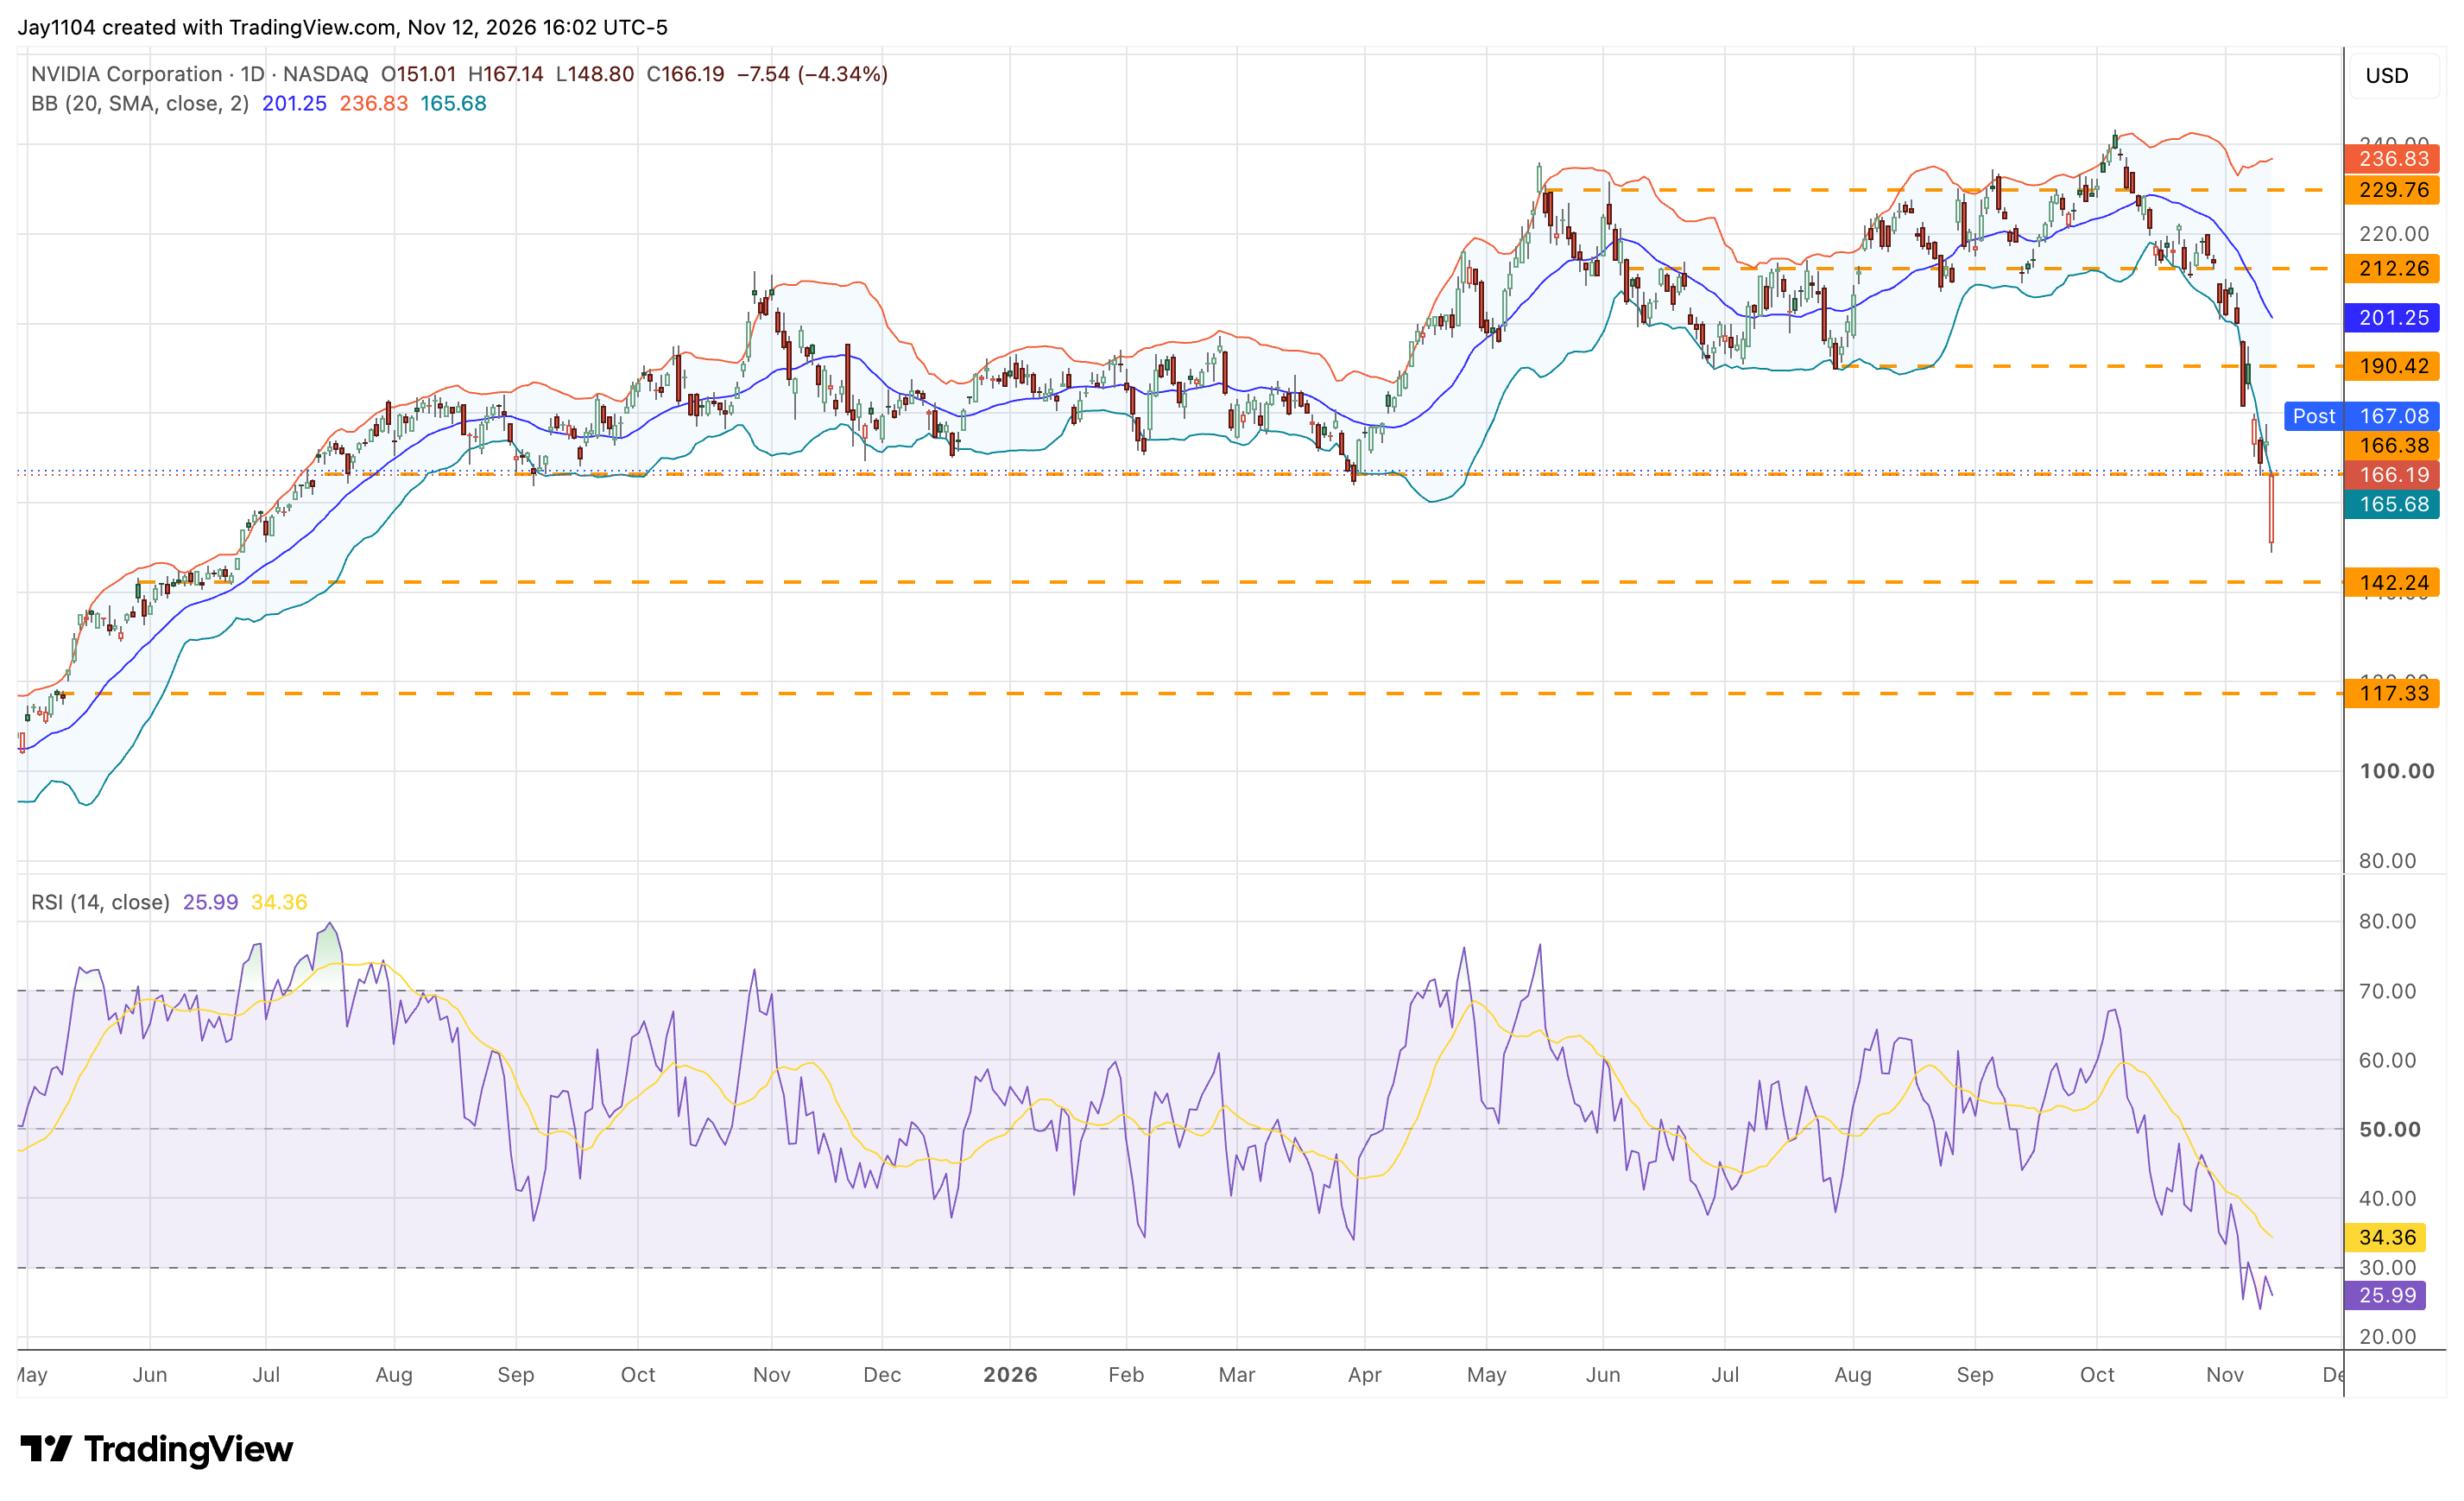
Given the sharp decline in its stock price over recent days, options positioning is very bearish, which means that once the company reports results and implied volatility resets, options hedging flows could unwind and push the stock higher. However, these results may not be business as usual. The normal mechanical unwinding of options positioning may be muted, given the uncertainty and risk that followed the sudden departure of the CEO. Currently, options positioning shows a concentration of call open interest at $200, which could offer resistance, and a concentration of put open interest at $150, which could offer support.
The stock is currently breaking through support that has held around $165 since July 2025, and if that continues, the stock could head back to $140, the next major support level. However, the stock is reaching oversold levels, as it falls through its lower Bollinger Band®, and the relative strength index falls below 30, suggesting it could be due for a bounce or a period of sideways consolidation.
Nvidia share price, May 2025 – present
Source: TradingView, 12 November 2026
US Fed minutes
Wednesday 18 November
Minutes from the Federal Open Market Committee (FOMC) meeting in October could shed light on why policymakers decided against a hike, and what that means for the path of future policy. The minutes come right after a stronger-than-expected jobs report and CPI inflation data, which suggests the Fed may have needed to increase rates. Currently, the market is pricing in a Fed rate hike at the December meeting.
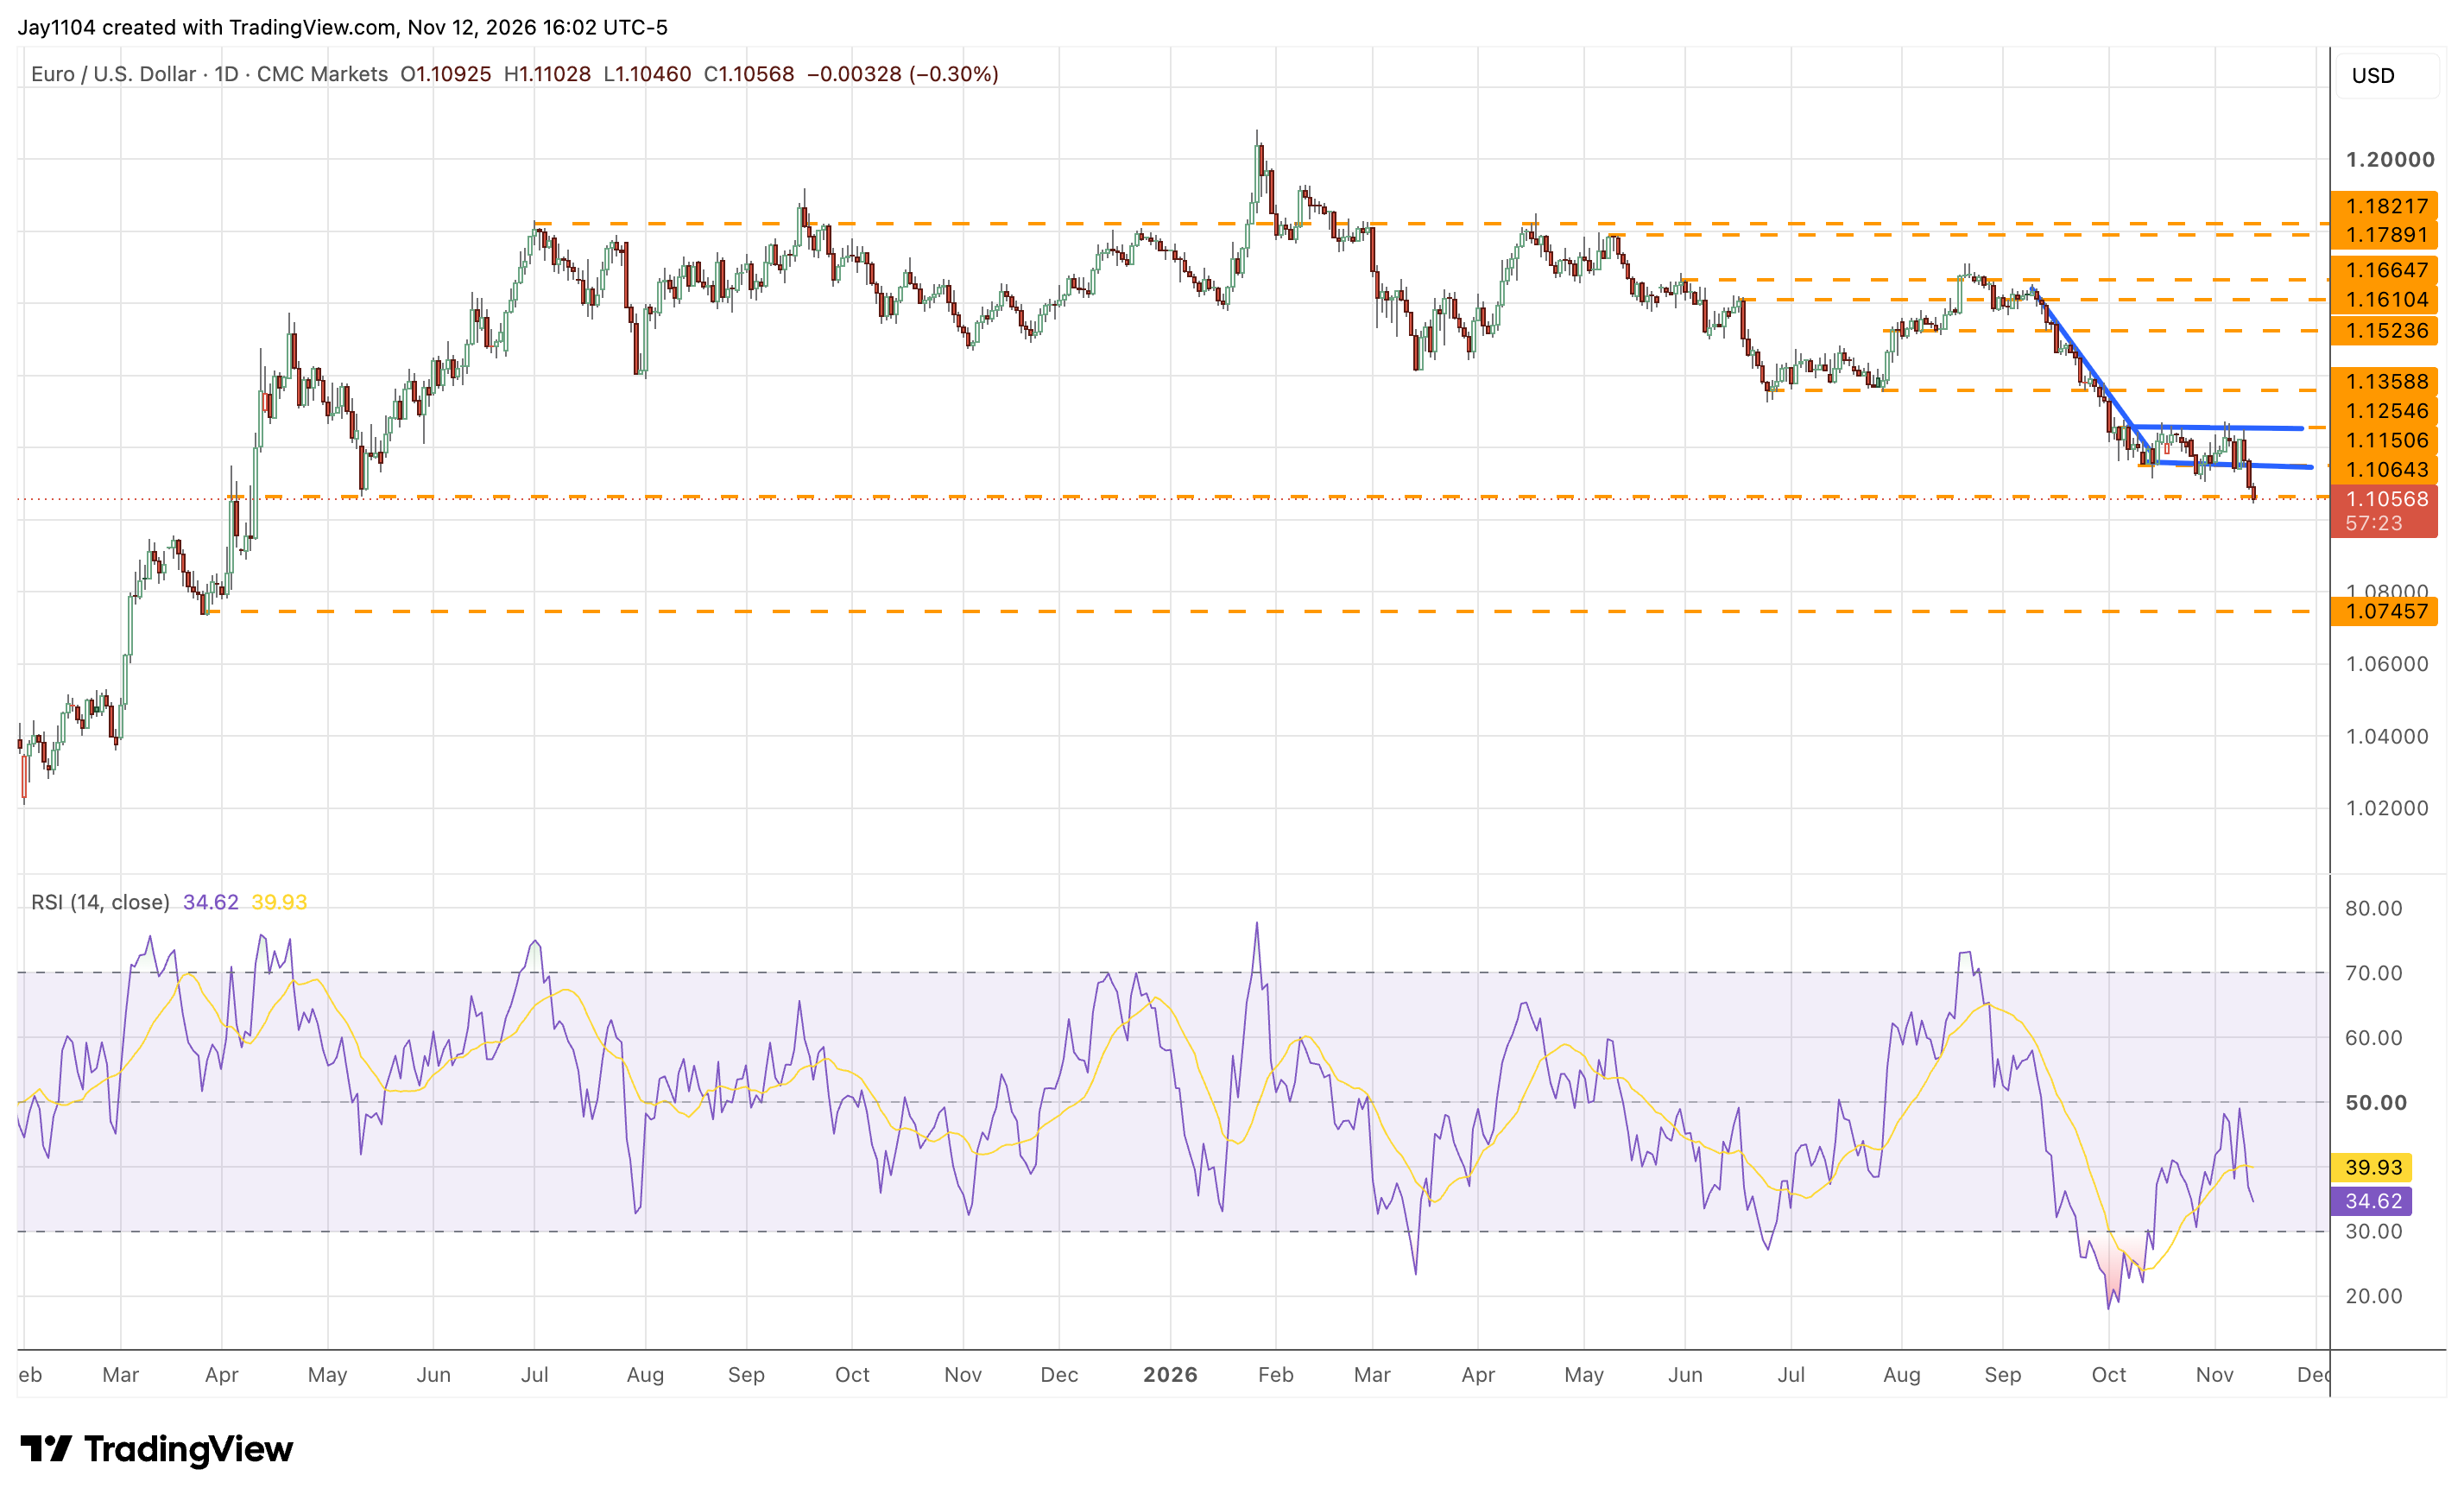
A hawkish read of the minutes could strengthen the dollar, and weigh on EUR/USD, which has just broken through support at $1.115 and is now testing the next support level at $1.105. A break below $1.105 would suggest a bear flag pattern is in effect, and with no clear support until $1.075, EUR/USD may be in for a steeper decline. For EUR/USD to rebound, the minutes may need to lean towards a policy of fewer rate hikes than the market is pricing in – but right now, given the economic data, that seems unlikely.
EUR/USD, February 2025 – present
Source: TradingView, 12 November 2026
Japan CPI
Thursday 19 November
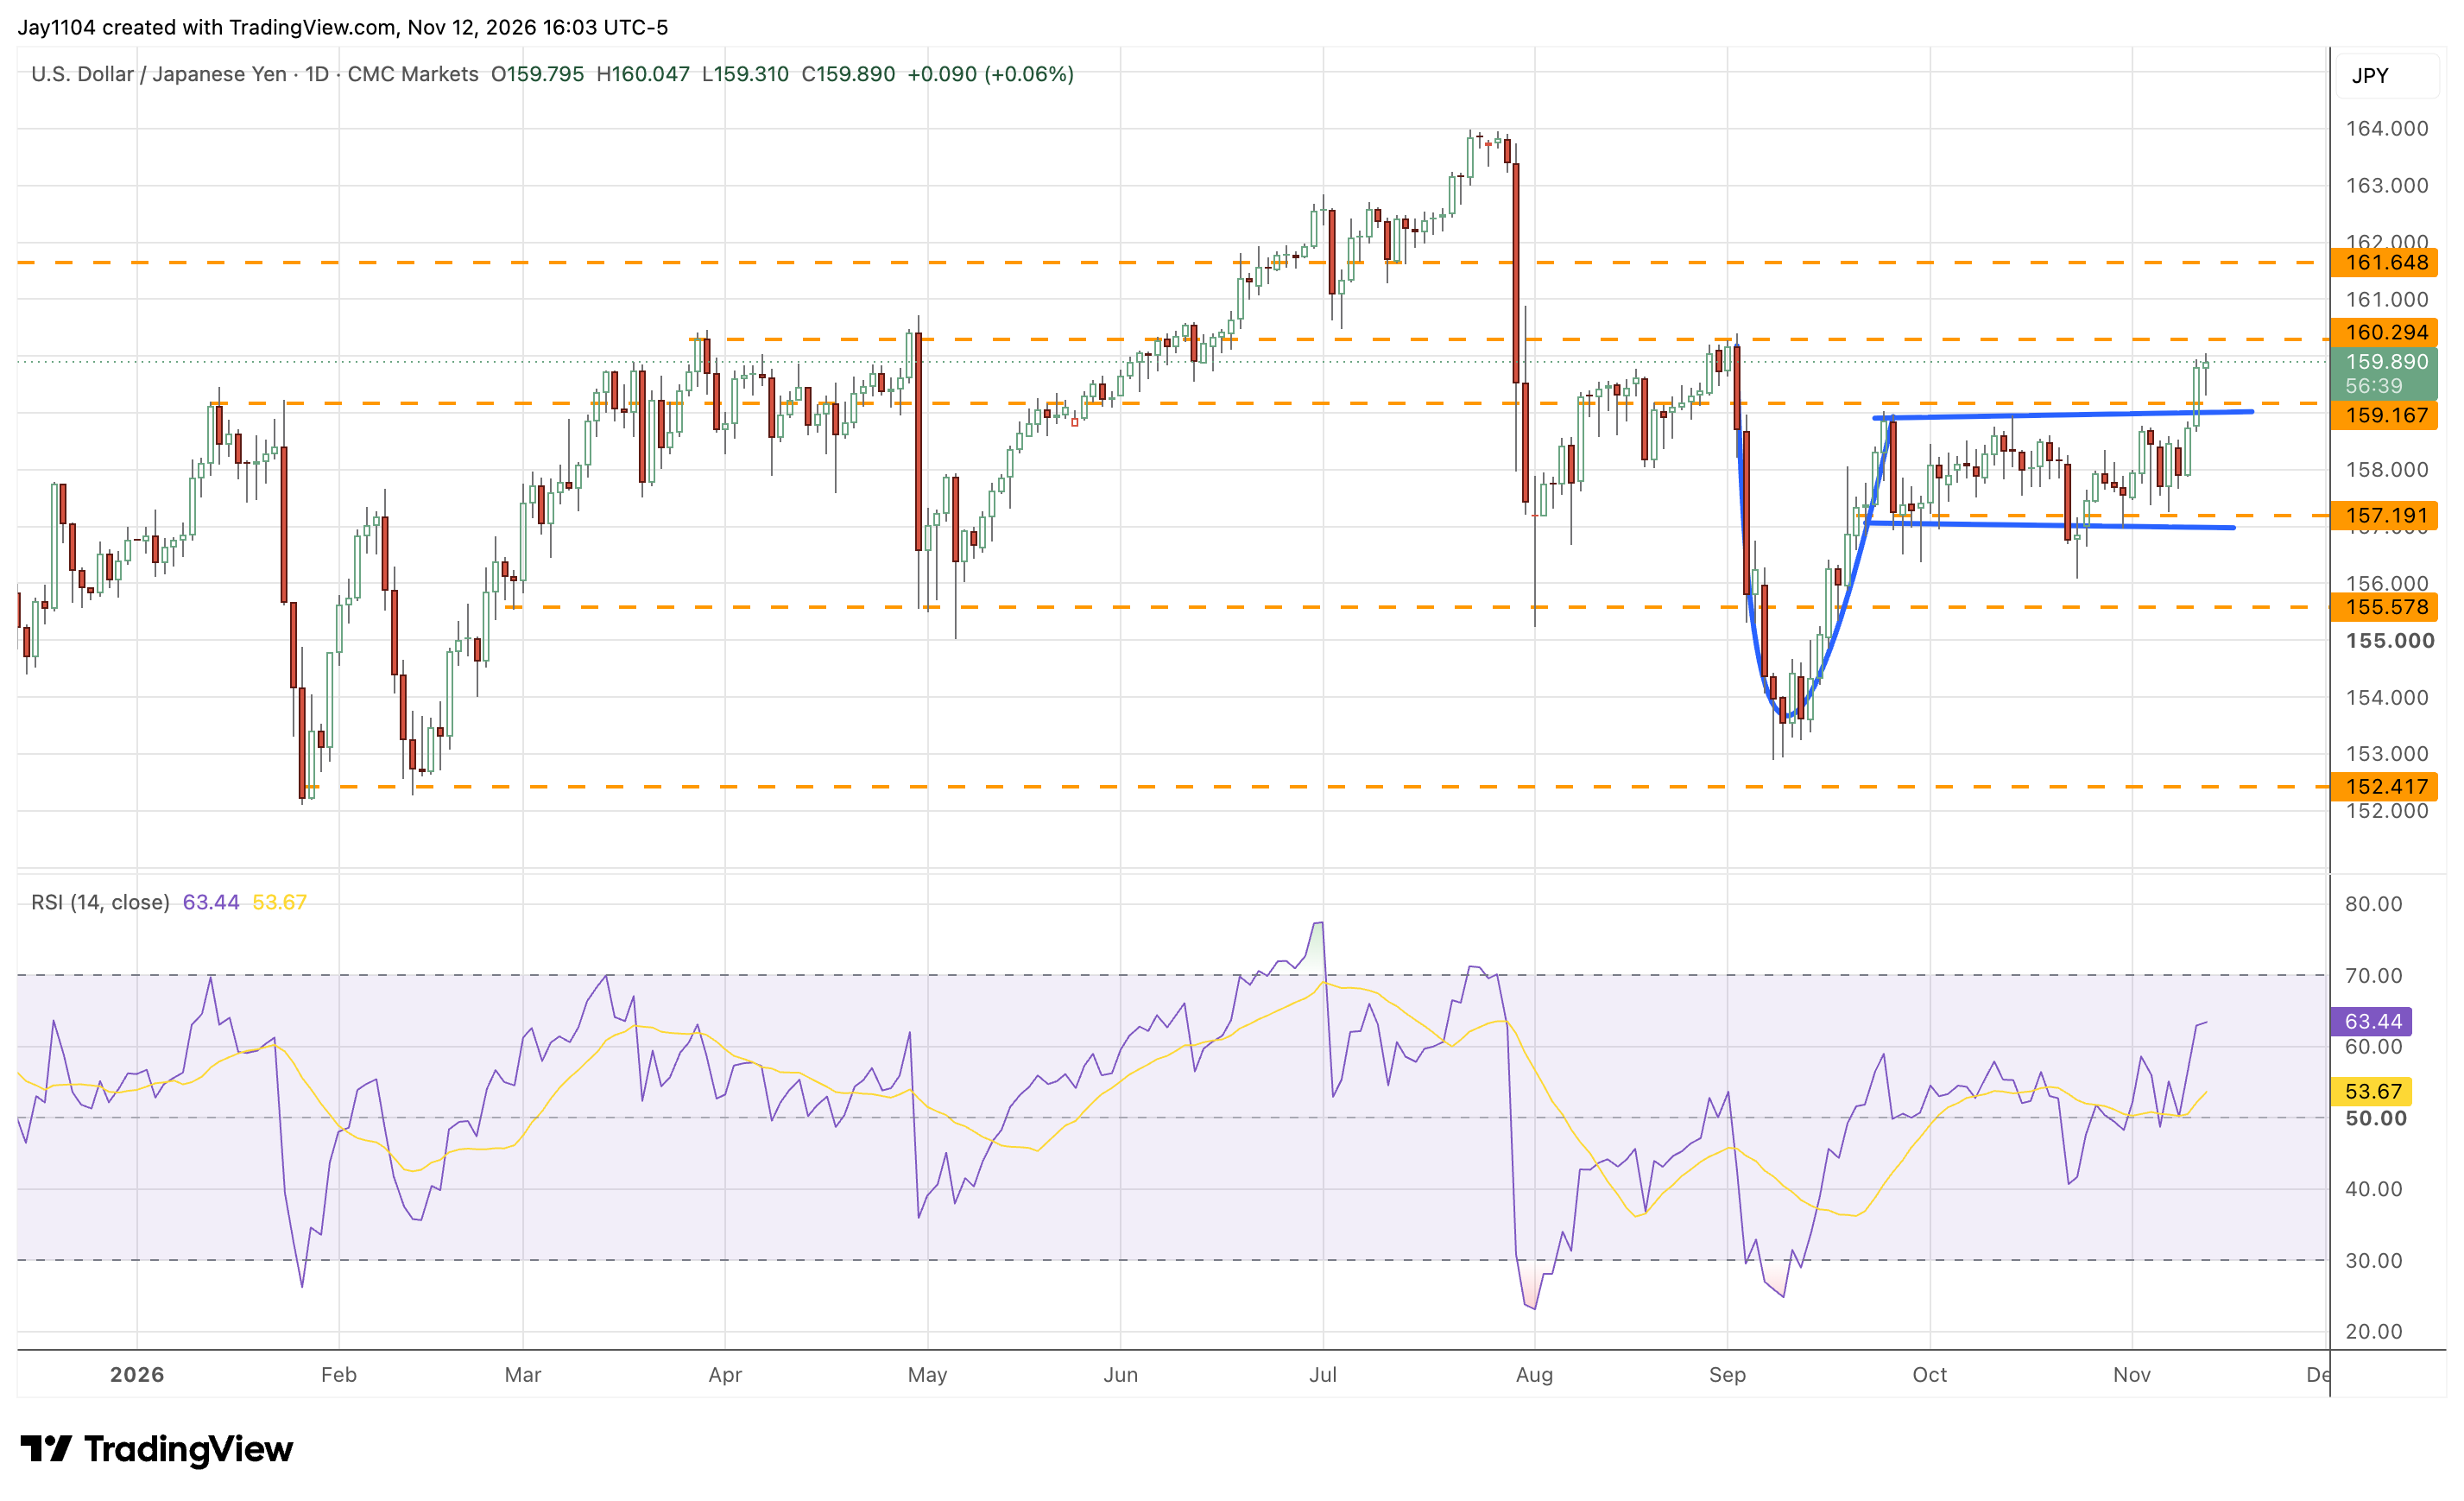
Inflation in Japan is expected to have accelerated in October, rising to 2.6% year-on-year from 2.1% in September, while core CPI is predicted to fall to 2.3% from 2.4%. A hotter reading will complicate matters for the Bank of Japan, and might persuade it to hike rates in December, even though the odds are mixed. It also comes as USD/JPY breaks out of a bullish continuation pattern, known as a cup-and-handle pattern, which could push it even higher as it approaches ¥160. A push beyond ¥160 may create a bigger issue in terms of potential Japanese government intervention, but it could ultimately threaten USD/JPY's rise back to resistance around ¥164.
USD/JPY, January 2026 – present
Source: TradingView, 12 November 2026
Economic & company events calendar
Major scheduled data releases, plus selected UK, US and other listed company results:
Monday 16 November
Canada: Consumer price index (October)
China: Industrial production, retail sales (October)
Eurozone: Industrial production (September)
US: NY Empire State manufacturing index (November)
Results: No major announcements
Tuesday 17 November
Eurozone: ZEW economic sentiment (November)
Japan: Trade balance (October)
UK: Average earnings (September), claimant count change (October), ILO unemployment rate (September)
US: Industrial production, retail sales (October)
Results: Diploma (FY), Home Depot (Q3), Imperial Brands (FY), Nvidia (Q3), Walt Disney (Q4)
Wednesday 18 November
Eurozone: CPI (October)
UK: CPI, producer price index, retail price index (October)
US: Building permits (October), FOMC minutes, housing starts, pending home sales (October)
Results: Palo Alto Networks (Q1), SSE (HY)
Thursday 19 November
Australia: Unemployment rate (October)
Japan: CPI (October)
US: Initial jobless claims (weekly), Philadelphia Fed manufacturing index (November)
Results: Halma (HY), Sage (FY), Walmart (Q3)
Friday 20 November
China: PBoC interest-rate decision
Eurozone: Consumer confidence (November)
Germany: PPI (October)
UK: Consumer confidence (November), retail sales (October)
US: University of Michigan consumer sentiment index (November)
Results: No major announcements
Note: While we check all dates carefully to ensure that they are correct at the time of writing, the above announcements are subject to change.