Third-quarter earnings face exceptionally high expectations
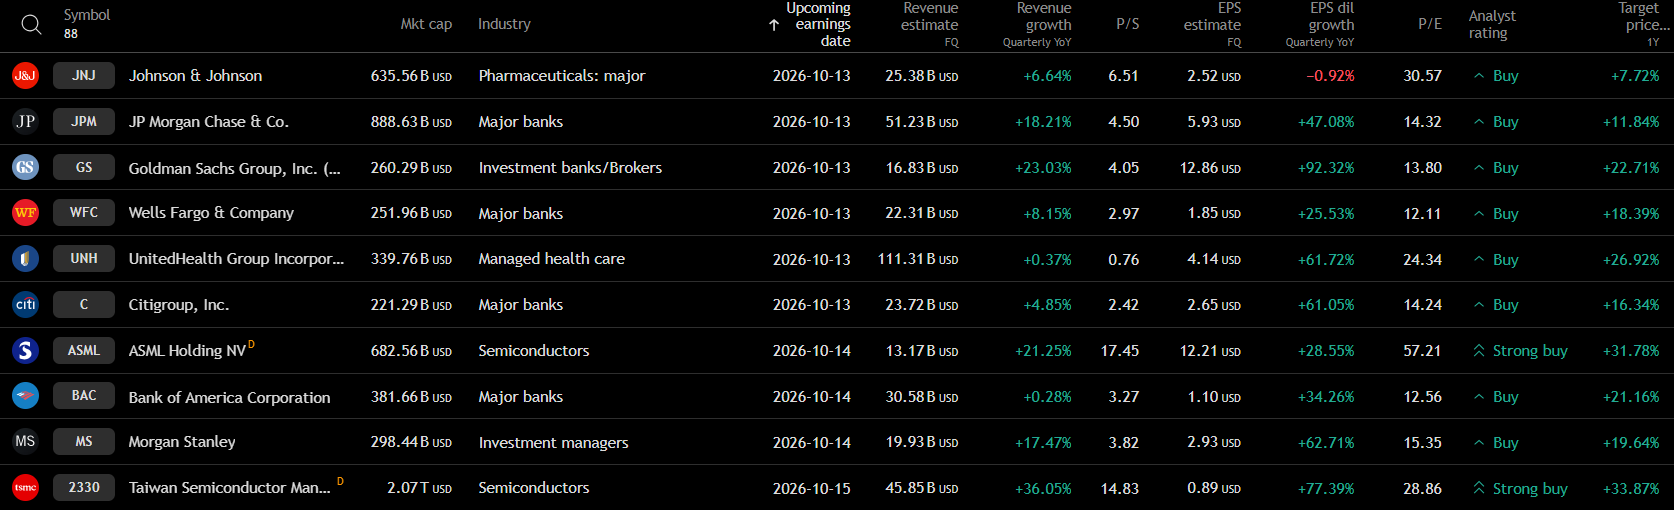
Analysts are approaching the third-quarter earnings season with considerable optimism. According to LSEG I/B/E/S estimates cited in the 13 October analysis, S&P 500 earnings are expected to grow 30.6% year on year in the third quarter of 2026 and 28.5% in the fourth. If achieved, the index would record four consecutive quarters with growth close to or above 30%, a sequence not seen since the reopening after the COVID-19 pandemic.
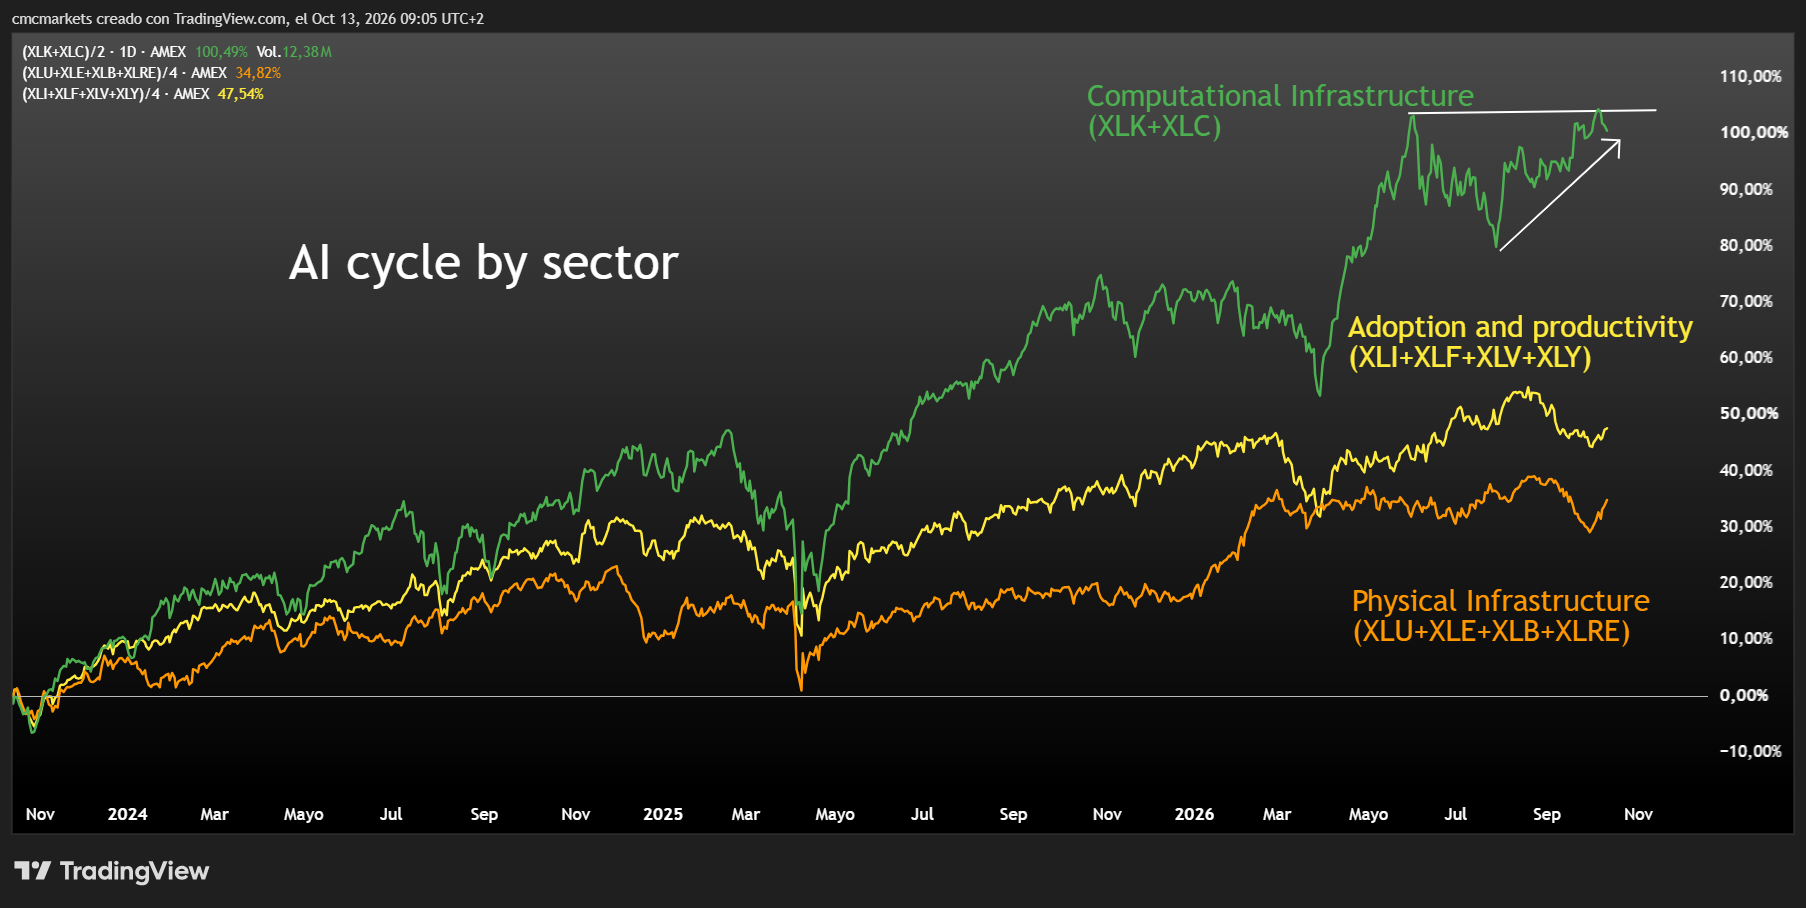
Companies' own forecasts reinforce these expectations. FactSet reports that 72 of the 116 companies that have updated their guidance have raised their projections, equivalent to 62% of the total. Technology accounts for much of the optimism, with 44 companies improving their estimates.
Analysts also retain a bullish outlook. FactSet's aggregate 12-month S&P 500 price target stands at 9,275.04 points, implying potential upside of close to 18%. All 11 sectors have projected upside above 10%, led by utilities at 28%, consumer discretionary at 26% and industrials at 25.1%. These are analyst forecasts, not guaranteed returns.
Demanding valuations and widening sector differences
Much of that expected growth may already be reflected in prices. The S&P 500 trades at a forward price-to-earnings ratio of 19.1 and a trailing ratio of 26, placing valuations around the 75th percentile of their historical ranges.
The comparison with fixed income raises the hurdle further. A price-to-earnings ratio of 26 implies an earnings yield of approximately 3.85%, below the 5.25% yield on ten-year US Treasury notes cited in the source analysis. The two measures are not directly equivalent, but the comparison illustrates the demanding equity valuations relative to interest rates.