The coming week could be one of the year’s most consequential, given recent market positioning, rising interest rates, and currency market volatility. Interest-rate announcements from the US Federal Reserve and the Bank of Japan, together with the latest UK inflation figures, could help determine whether traders and investors unwind recent positions or add to them.
The Week Ahead: US Federal Reserve, Bank of Japan, UK inflation
CMC Markets
Table of contents
- 1.US Federal Reserve meeting
- 2.Bank of Japan meeting
- 3.UK CPI
- 4.Economic & company events calendar
US Federal Reserve meeting
Wednesday 16 September
Markets now price an 86% chance of a rate hike at this week’s FOMC meeting (per CME FedWatch), following recent hotter inflation data. A 25 bp increase is the base case.
Traders will still focus closely on the Fed’s policy guidance at the post-meeting press conference. The meeting also includes the Summary of Economic Projections (the “dot plot”). Changes to that format remain possible under Chair Kevin Warsh, though it is unclear whether any formal adjustments will be announced this week.
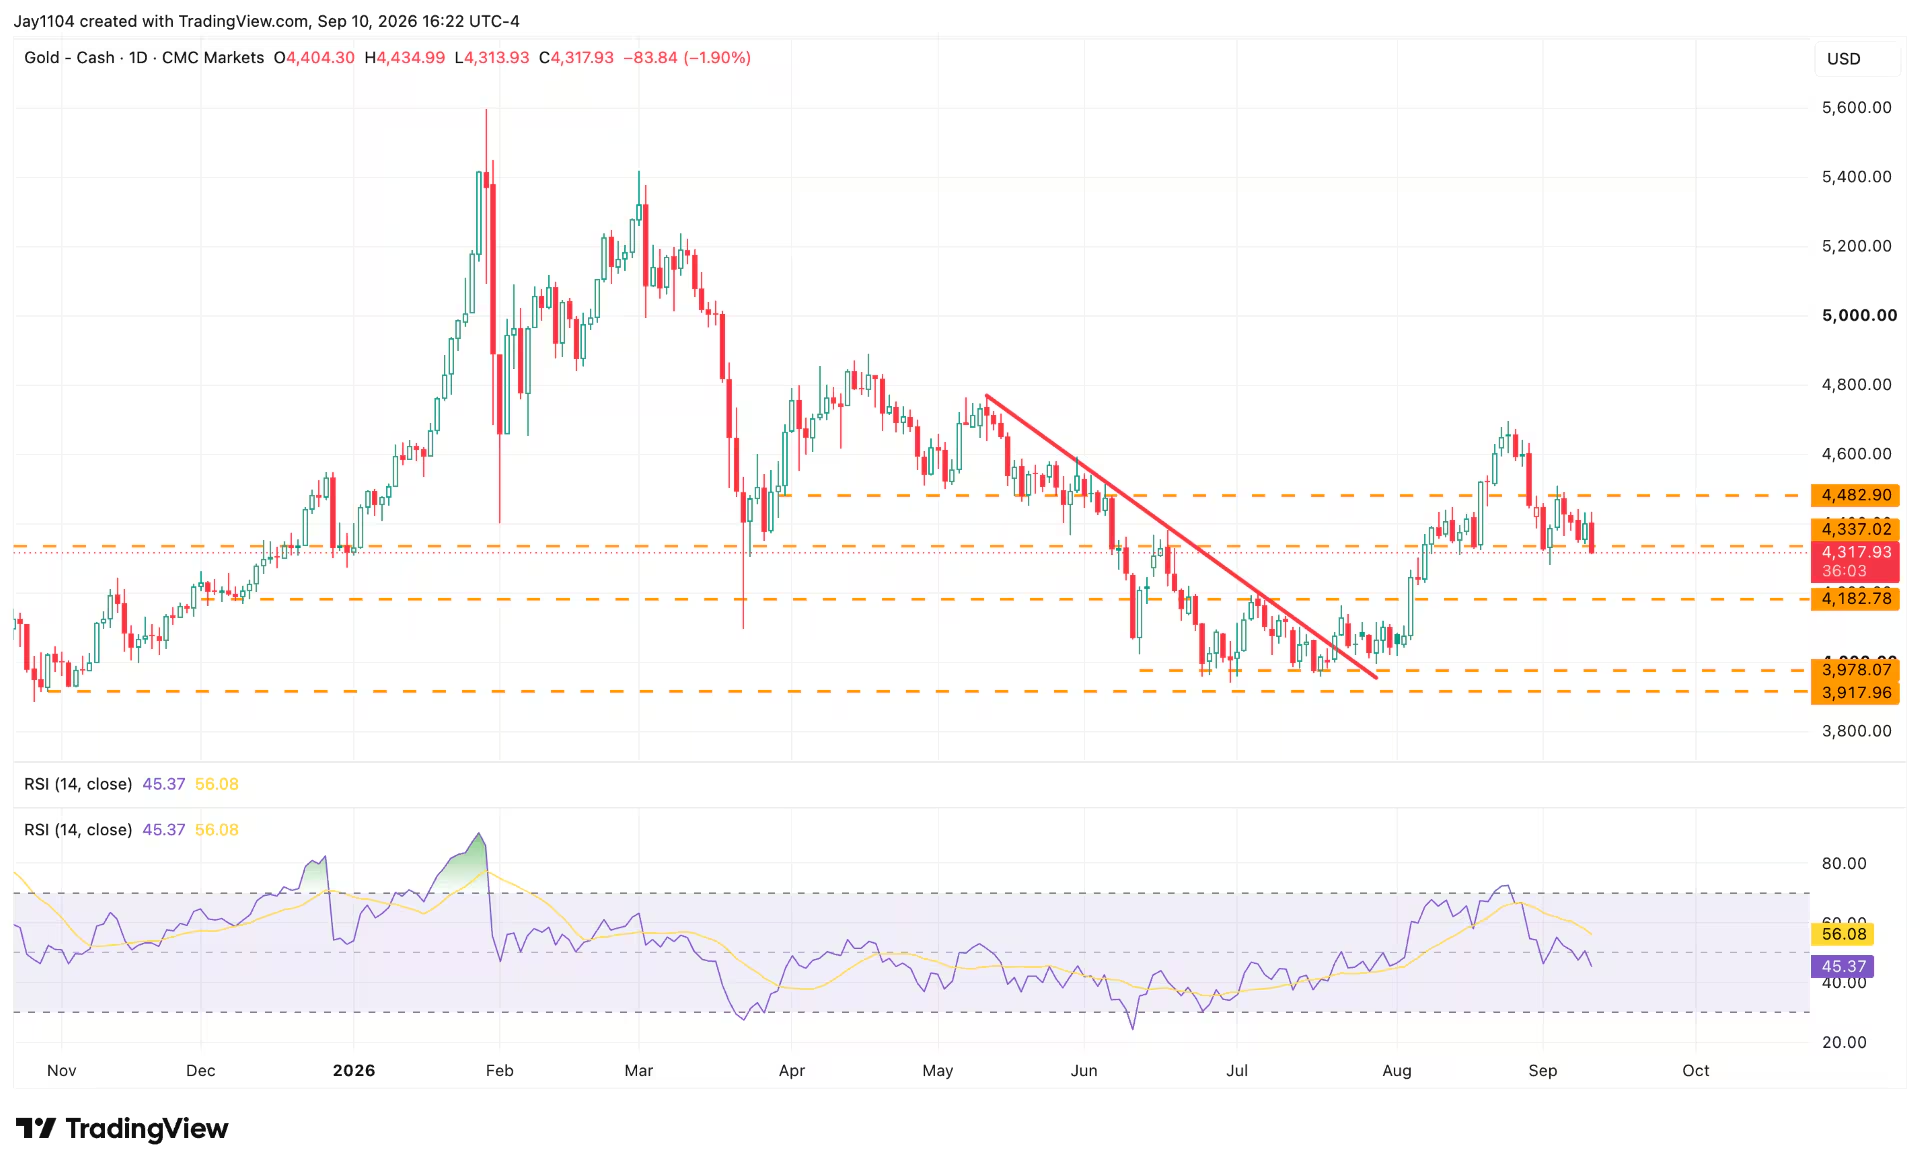
A confirmed hike, combined with any hawkish guidance from Warsh, could weigh on gold. The metal recently pushed toward $4,685 before retreating to around $4,350. A break below support at $4,300 on a more restrictive Fed message could open the way toward $4,000, with a further decline potentially exposing $3,700.
Conversely, if gold holds the $4,350 area and the press conference tone comes across less hawkish than currently priced, prices could still attempt a retest of the recent highs near $4,685.
Gold - Cash, November 2025 – present
Sources: TradingView, Michael Kramer
Bank of Japan meeting
Friday 18 September
Markets are pricing around a 98% chance of a Bank of Japan rate hike, with another increase widely expected in December 2026 or January 2027. This remains important for global markets, as the yen has already strengthened significantly against several major currencies on the rising odds of tighter Japanese policy.
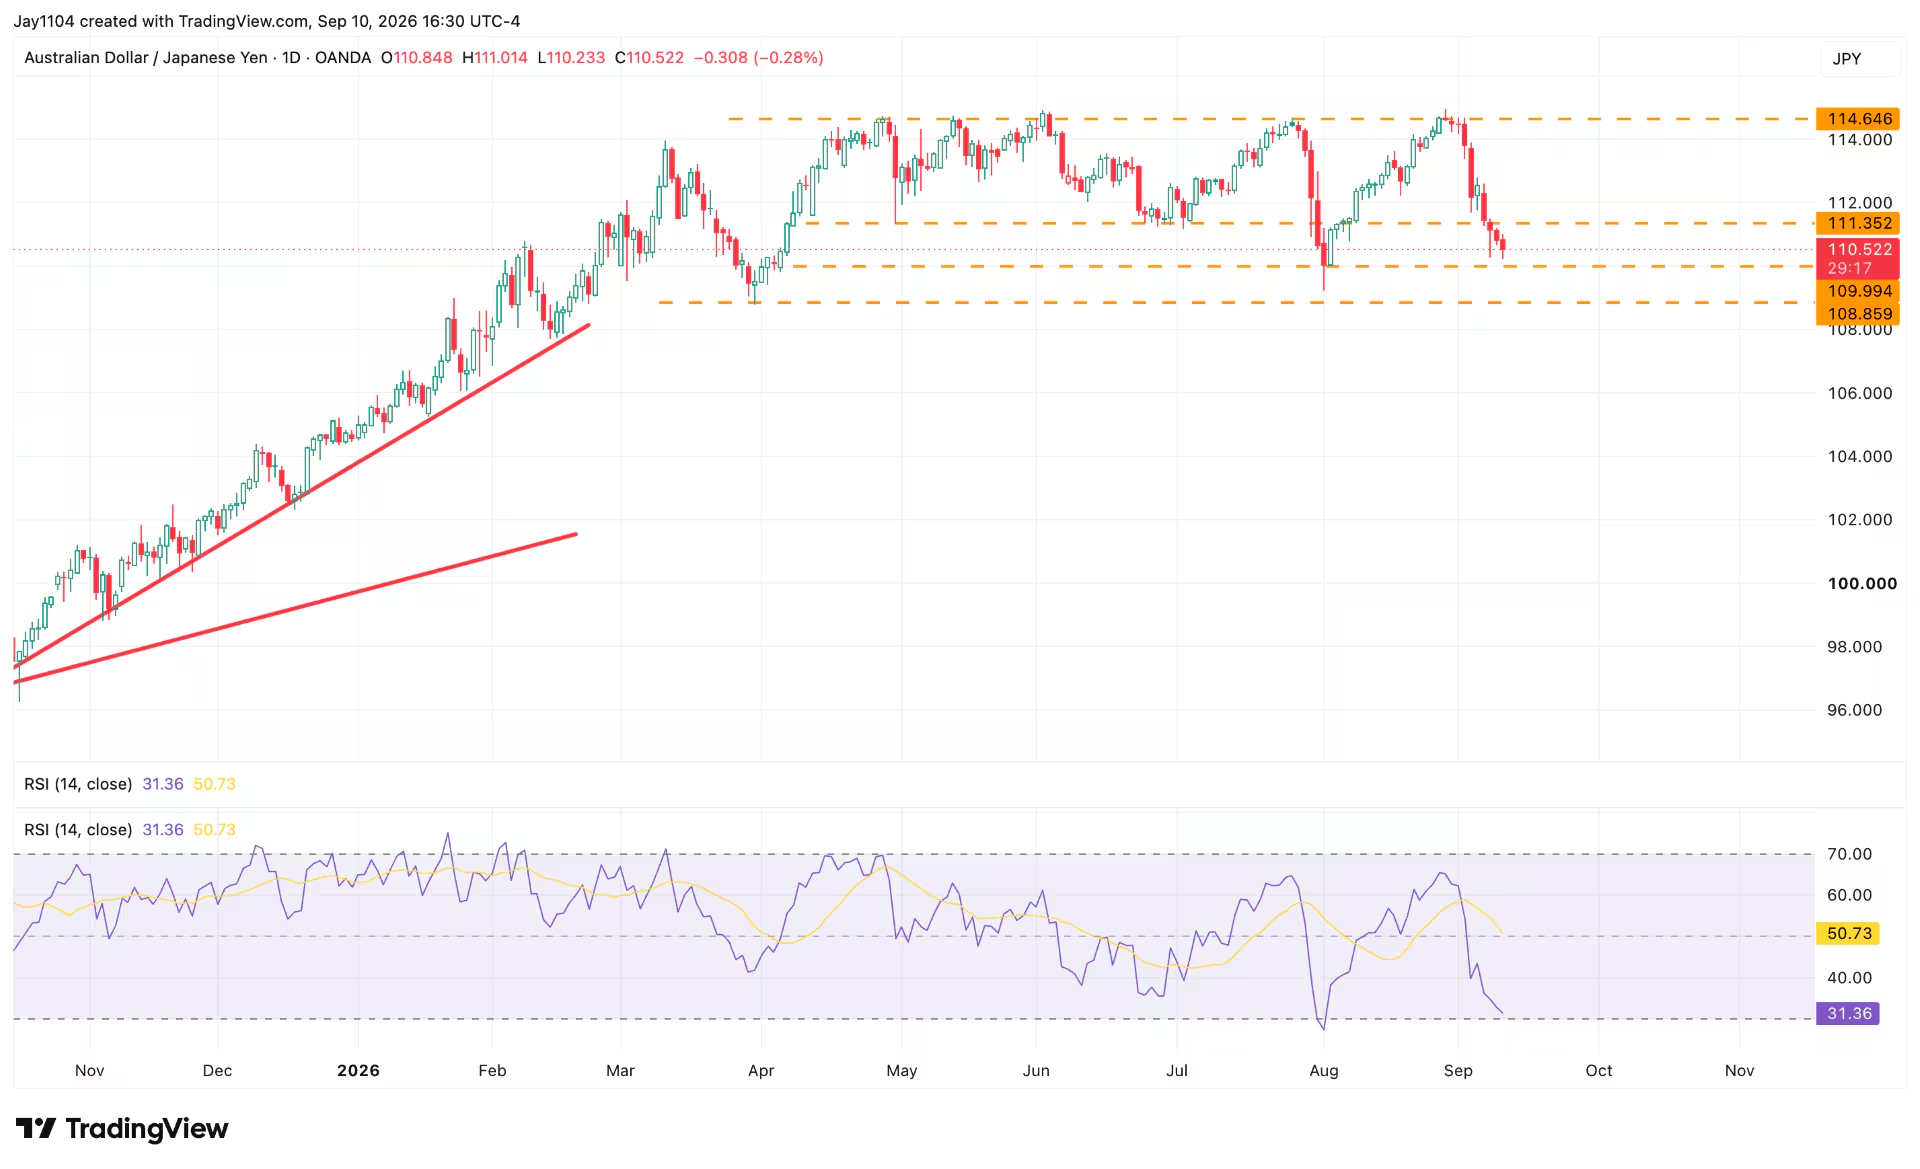
AUD/JPY is trading near a critical support zone between ¥109 and ¥110. A break below this area, especially if accompanied by hawkish commentary from the BoJ, could open the way toward ¥107.50. The larger risk is that higher Japanese interest rates raise the cost of borrowing yen, which may accelerate an unwinding of the global carry trade and keep AUD/JPY under sustained pressure. This could signal a broader regime shift toward stronger yen performance across multiple currency pairs.
However, if the Bank of Japan disappoints by holding rates or delivering a more dovish outlook than currently priced, AUD/JPY could rebound toward ¥115, the upper end of its recent trading range.
AUD/JPY, November 2025 – present
Sources: TradingView, Michael Kramer
UK CPI
Wednesday 16 September
UK headline and core CPI inflation appear to be bottoming out, with both annual rates edging higher last month. Analysts expect headline inflation to rise further, from 2.9% to 3% year-on-year. Against this backdrop, markets are pricing in a rate hike from the Bank of England in November – which would take the UK base rate from 3.75% to 4% – with a further increase to 4.25% possible in December.
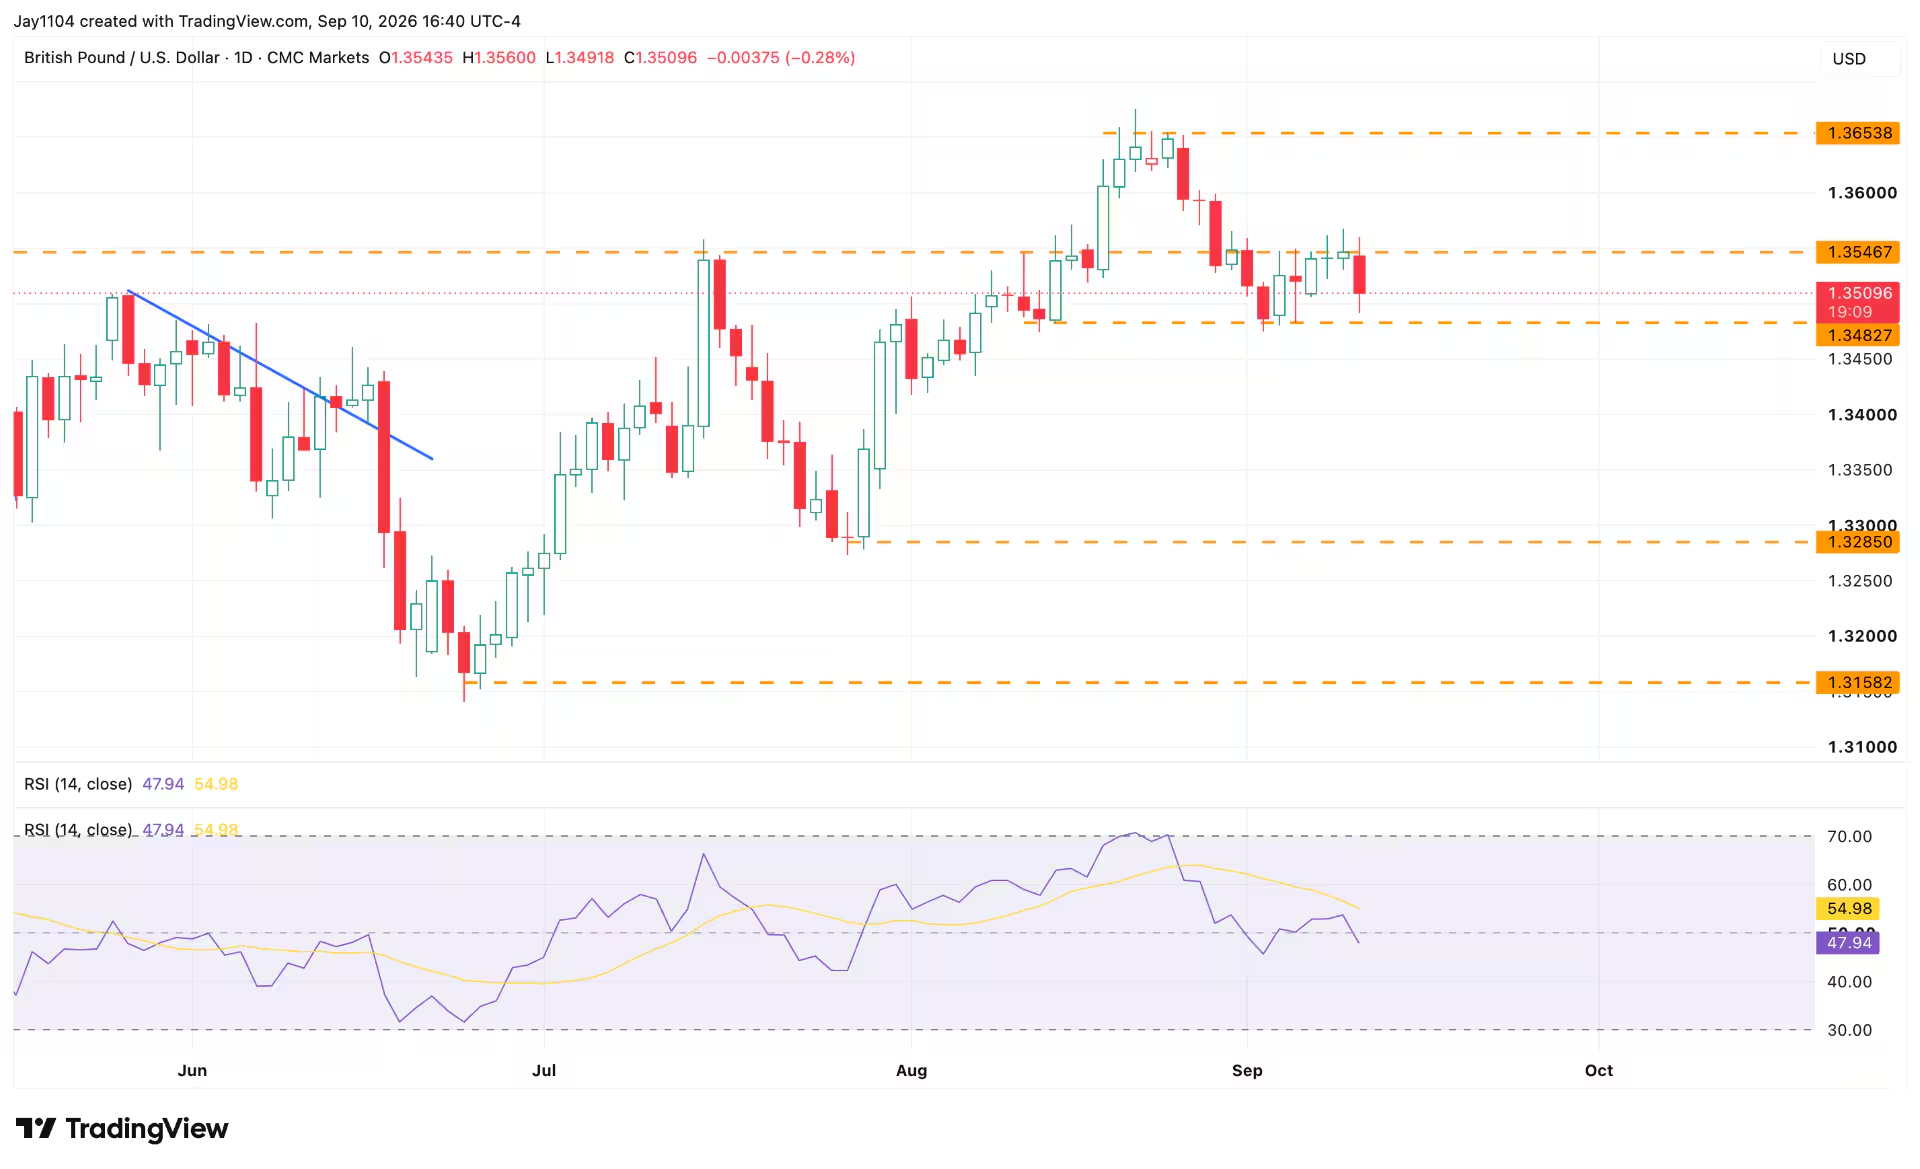
The lingering question is whether the CPI report could bring those expectations forward to the 17 September meeting. At this point, that seems unlikely unless the data delivers a significant surprise. Meanwhile, a cooler reading may reduce tightening expectations, potentially weighing on GBP/USD, which has recently stabilised around $1.35.
A break below $1.348 could see the pound fall towards $1.328, the next major support area. If support holds, GBP/USD could rise towards $1.365, with the potential to break higher.
GBP/USD, June 2026 – present
Sources: TradingView, Michael Kramer
Economic & company events calendar
Major scheduled data releases, plus selected UK, US and other listed company results:
Monday 14 September
• Canada: August consumer price index (CPI)
• Results: Big Technologies (HY), GlobalData (HY), Kestra Medical Technologies (Q1), MP Evans Group (HY)
Tuesday 15 September
• China: August industrial production, retail sales
• UK: July ILO unemployment rate, average earnings
• US: ADP employment change, September Empire State manufacturing index
• Results: Kier Group (FY), Trip.com (Q2), Trustpilot (HY)
Wednesday 16 September
• Eurozone: July industrial production
• Japan: August exports, imports
• UK: August CPI, producer price index (PPI), retail price index
• US: August retail sales, Federal Reserve interest-rate decision, monetary policy statement, FOMC press conference
• Results: Barratt Redrow (FY), Dollarama (Q2), Supermarket Income REIT (FY)
Thursday 17 September
• Eurozone: August CPI
• UK: Bank of England interest-rate decision, minutes, monetary policy summary
• US: August building permits, housing starts, pending home sales, September Philadelphia Fed manufacturing survey
• Results: Galliford Try (FY), Lennar (Q3), Next (HY)
Friday 18 September
• Japan: August CPI, Bank of Japan interest-rate decision, monetary policy statement, press conference
• UK: August retail sales
• US: August industrial production
• Results: No major announcements
Note: Announcements and dates are subject to change. Cross-check times in your timezone using the platform market calendar.
Disclaimer: This article provides general information only. It has been prepared without taking account of your objectives, financial situation or needs. It is not to be construed as a solicitation or an offer to buy or sell any financial instruments, or as a recommendation and/or investment advice. It does not intend to support an investment decision and it should not be relied upon by you in evaluating the merits of investing in any financial instruments. You should consider your objectives, financial situation and needs before acting on the information in this article. CMC Markets believes that the information in this article is correct, and any opinions and conclusions are reasonably held or made on information available at the time of its compilation, but no representation or warranty is made as to the accuracy, reliability or completeness of any statements made in this article. CMC Markets is under no obligation to, and does not, update or keep current the information contained in this article. Neither CMC Markets nor any of its affiliates or subsidiaries accepts liability for loss or damage arising out of the use of all or any part of this article. Any opinions or conclusions set forth in this article are subject to change without notice and may differ or be contrary to the opinions or conclusions expressed by any other members of CMC Markets.